A takeover bid for lifestyle village operator Ingenia has been sweetened twice and still falls short of analyst price targets. The gap between what bidders are offering and what the portfolio appears to be worth on fundamentals points to a broader question: are listed property vehicles trading at a structural discount to their underlying cash flow and land value?
The Ingenia valuation gap matters because it’s not unique. When a business with long-term recurring income and hard assets trades persistently below what those components are worth separately, something is keeping buyers away, or keeping sellers from accepting realistic offers. For anyone tracking listed property as an investment class or comparing direct ownership to fund exposure, the mechanics of this mismatch are worth understanding.
What’s driving the discount
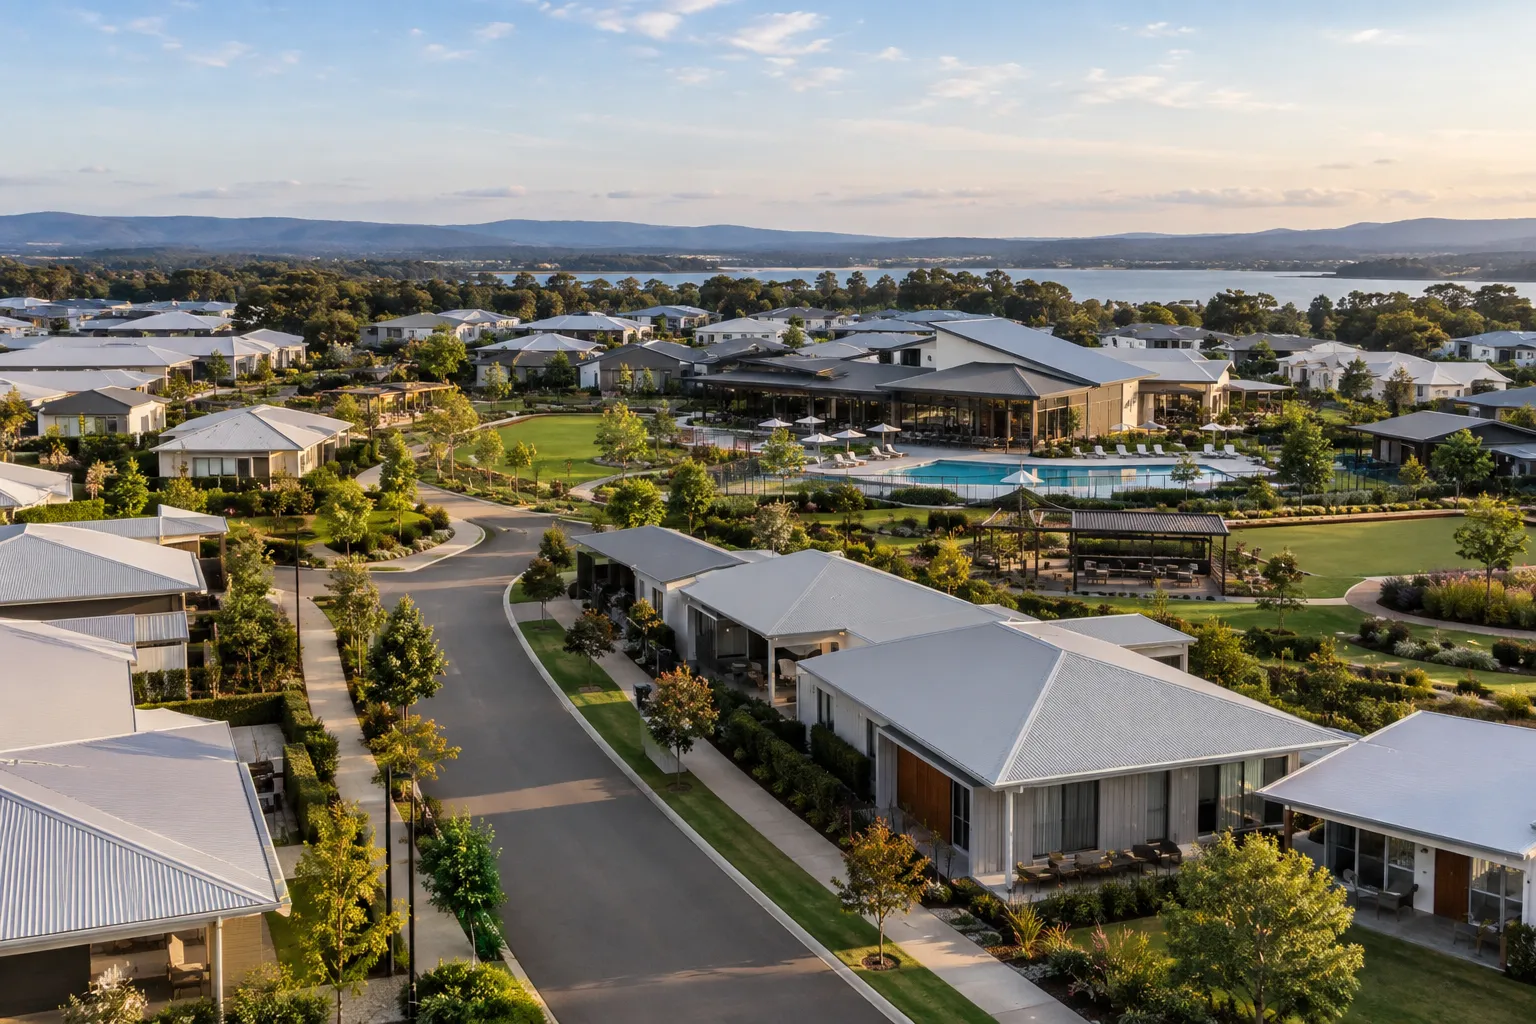
Lifestyle villages generate predictable income from site fees and deferred management fees when residents leave. Land is finite, zoned, and typically appreciates over time. On paper, that should command a premium. In practice, listed vehicles face three headwinds.
First, liquidity concerns. Institutional buyers want scale and exit optionality. A portfolio heavy in single-use assets (villages can’t easily be repurposed) narrows the buyer pool. Second, the market prices in execution risk, village development timelines stretch across years, and demand can shift if migration slows or downsizer sentiment changes. Third, listed property trusts often trade at a discount to net tangible assets during periods of rising rates, because investors compare yields to bonds and price in refinancing risk.
None of those factors erase the underlying value. They just explain why a bidder might lowball and why the board might hold out for more.
Who this affects beyond Ingenia shareholders
If you own units in a listed property trust with exposure to retirement living, land lease communities, or similar long-cycle assets, you’re seeing the same discount play out in your own portfolio. The mismatch creates opportunity if you believe cash flow is durable and land value holds, but it also means your unit price can lag fundamentals for years.
For direct property investors, the gap is a reminder that asset class matters as much as location. A well-located village parcel might be worth more to a private buyer than to a listed fund constrained by hurdle rates and liquidity mandates. That’s not a criticism of listed vehicles, it’s just a structural difference in how value is assessed.
Scenarios that would close the gap
Three things could bring bid price and analyst targets closer together. First, a competing bidder with a longer time horizon and lower cost of capital (superannuation funds fit this profile). Second, an earnings beat that proves the income stream is more resilient than priced in, especially if migration and downsizer demand stay strong. Third, a broader repricing of property yield expectations if rate cuts arrive faster or deeper than the market currently expects.
The downside scenario: if the bid fails and no competing offer emerges, the stock drifts back toward its pre-bid price, locking in the discount for another cycle.
What to watch over the next quarter
Three data points will clarify whether the valuation gap is justified or overblown. First, village occupancy and new resident inquiry numbers, if demand softens, the income assumption weakens. Second, comparable transactions in the unlisted space (private equity and super funds buying villages directly). Third, refinancing announcements from other listed property trusts, if borrowing costs stay elevated, the discount persists.
Key numbers
- Bid value exceeds $3 billion after two increases, still below analyst consensus price targets
- Lifestyle village portfolios typically generate recurring income from site fees and deferred management fees on resident turnover
- Listed property trusts often trade at a discount to net tangible assets during rising rate cycles
- Village development timelines stretch across multiple years, pricing in execution and demand risk
Practical take for investors
If you hold listed property exposure, check how much of your portfolio sits in long-cycle, single-use assets like retirement villages or land lease communities. The discount to fundamentals can persist for years, even when cash flow is solid. That’s fine if you’re holding for income and don’t need liquidity, but it’s a drag on total return if you’re comparing to other property sectors.
For anyone considering direct property investment in retirement living or similar niches, the Ingenia bid shows that private market valuations can run ahead of listed prices. That’s an opportunity if you can access the asset class outside the ASX, but it also means exit liquidity is thinner if you need to sell in a hurry.
If you want the weekly breakdown of what’s moving Australian property markets and why, subscribe to the newsletter.
General info, not financial advice.