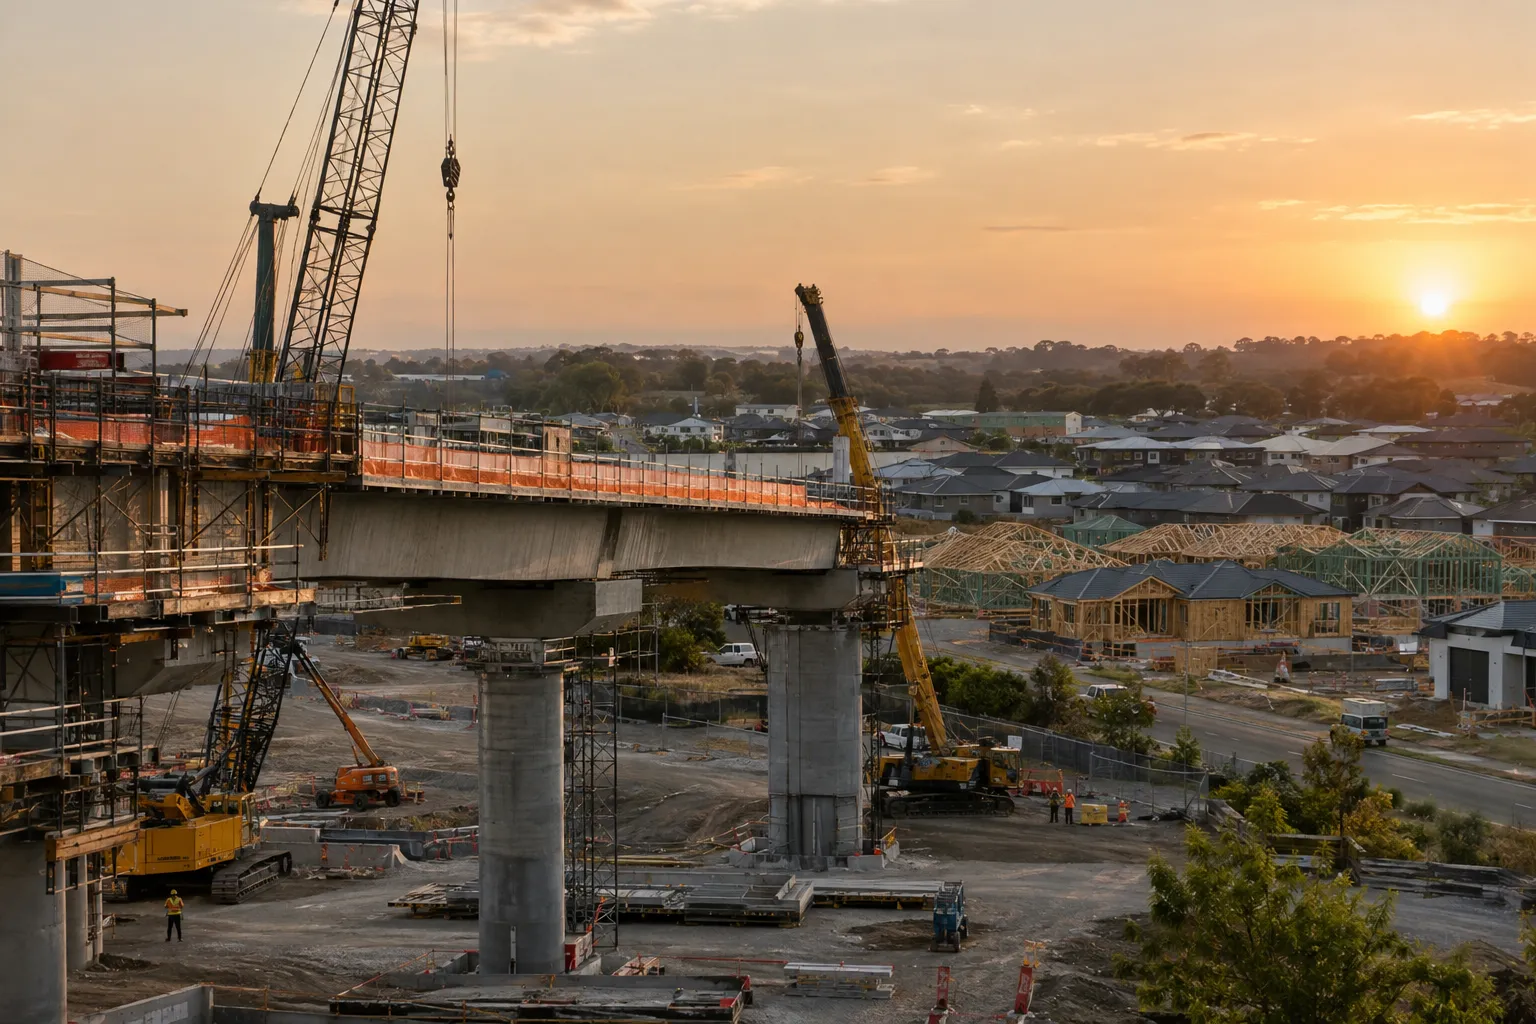
A reported $242 billion infrastructure pipeline is being framed as a productivity opportunity. That is the headline version. The version that matters for property is simpler: the same pool of builders, engineers and trades has to deliver roads, rail and civic projects as well as the homes governments have promised.
This piece works from the headline figure and public context only. Project-level detail, timing and funding splits are not confirmed here, so treat the numbers below as a framing, not a forecast.
Why an infrastructure pipeline housing story is really about capacity
Infrastructure and housing draw on overlapping inputs. Civil contractors, project managers, concrete, steel and skilled labour do not come in separate national supplies. When a large pipeline of public work is released, it competes for the same workforce that residential builders need.
That matters because housing delivery is already behind. The housing accord shortfall is a reminder that the target is not being met even before a big infrastructure wave lands.
In plain English
- Infrastructure and housing compete for the same builders and trades.
- More public work can mean slower or costlier home delivery.
- The effect is uneven by state and by project timing.
The builder pool is thinner than the pipeline implies
A headline number says what governments plan to spend. It says nothing about who will build it. Capacity is the binding constraint, and the sector has been under strain. The second wave of construction insolvencies looks likely, which means some capacity may exit just as demand for it rises.
When contractors fail, experienced crews and project knowledge go with them. Rebuilding that takes years, not quarters.
Two things follow:
- Public projects can win the best contractors with better-funded, lower-risk contracts.
- Private residential builders, often on thinner margins, can be left with the harder labour market.
That is a trade-off, not a certainty. Some infrastructure work uses specialist civil skills that homebuilders do not, so the overlap is partial.
Where the pipeline can lift property demand
Infrastructure does not lift every suburb. It tends to change the appeal of specific corridors: stations, motorway interchanges, airports and employment hubs. Better access can widen the pool of buyers and renters who will consider a location.
The usual lag is long. Announcement effects can appear early, completion effects later, and construction disruption can weigh on an area in between.
A rule of thumb: the closer a project is to funded delivery, the more credible the demand signal. A line on a plan is not the same as a contract awarded.
What this means for supply timing
Housing approvals and starts are only part of the story. Delivery depends on whether builders can actually get to a site. The pipeline for new homes already looks fragile in places, with building starts lifting while the pipeline thins.
Approvals are another drag. When it takes years to clear a single project, as shown in the 12-year approval timeframes example, adding competing demand for construction labour does not help the timeline.
Risks and unknowns
- Pipeline figures are plans, not commitments. Projects slip, shrink or get cancelled.
- Cost inflation in materials and labour can erode both infrastructure and housing budgets.
- State budgets are stretched, so funding can be re-prioritised.
- Population growth and migration settings shift housing demand independently of any pipeline.
Base case: a gradual squeeze on construction capacity that adds to cost pressure but does not stop housing delivery outright. Downside: a bunching of major projects that pulls labour away from residential building in specific states. Upside: coordinated sequencing that spreads demand and adds workforce training.
What readers can do with this
If you invest or buy near a proposed project, check whether it is funded and when construction is scheduled. If you are watching new-build supply, track builder insolvencies and tender pricing alongside approvals, because those signal whether homes will actually be delivered.
For the weekly signal on policy, supply and credit, subscribe to the newsletter.
General info, not financial advice.