Two numbers from the latest PropTrack investor data pull in opposite directions. Overall investor loans fell 9%. Lending for investors buying or building new homes rose 24%. Read together, they describe investors changing what they buy, not whether they buy.
That distinction matters more for renters than for landlords. Here is why.
Two loan books moving in opposite directions
The 9% fall sits on top of a post-budget dip in demand that has since partly recovered but still trails last year’s peak. The 24% rise sits inside it. In other words, the existing-home side of investor lending is shrinking faster than the headline suggests, because new-build lending is propping up the total.
This is what a policy-driven shift looks like. When the tax treatment of existing homes gets less generous and new homes keep their appeal, money follows the rules. Investors are not irrational. They are re-pricing.
One caution: the figures given here do not break out how large the new-build slice is relative to the whole. A 24% jump from a small base can look dramatic without changing the overall picture much. Treat it as a direction, not a verdict.
Why the rental pool shrinks before it grows
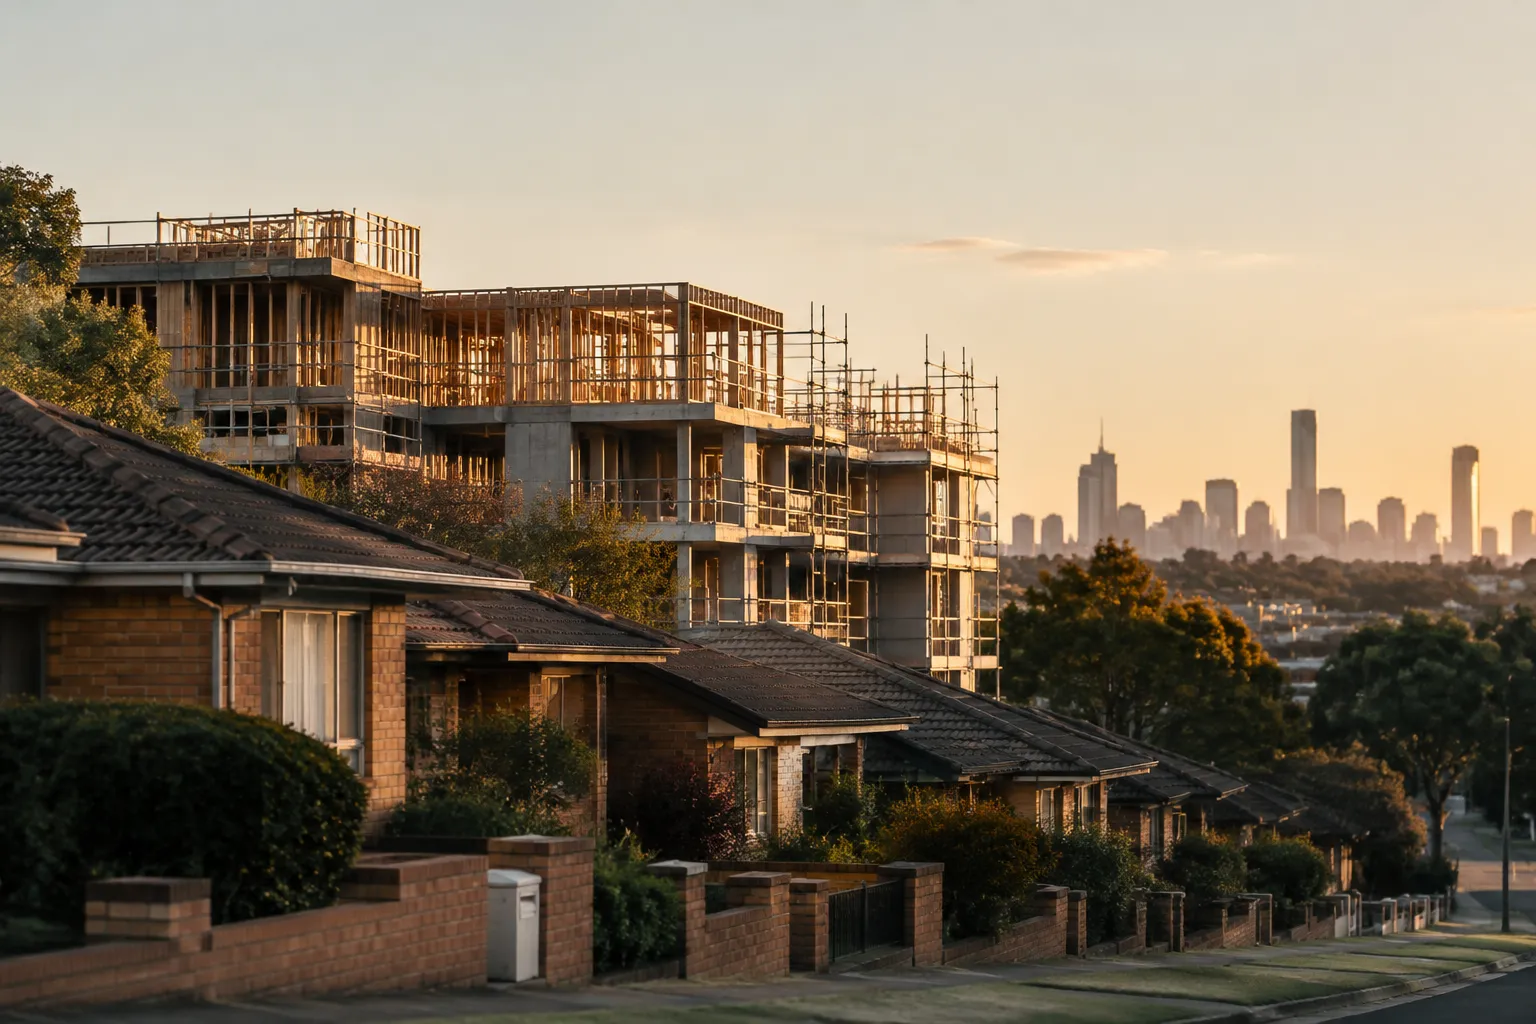
An investor who buys an existing house usually adds a rental to the market within weeks, because many of those homes already have tenants or can be let quickly. An investor who funds a new build adds a rental only once construction finishes, often a year or more later.
So even if total investor dollars held steady, the timing would hurt tenants. Existing-home investors who step back remove rentals from the near-term pipeline. New-build investors add them later. The gap in between is where rents bite.
The pressure is already visible. Rents sit 5.5% above a year earlier. Capital city dwelling values slid 4.3% over the September quarter, which is the sort of softening that usually tempts investors back in. Falling prices can lift yields, and yield is exactly what investors are now chasing, with online enquiries leaning towards higher-yielding, self-funding rentals.
Key numbers
- Investor loans: down 9%
- New-home investor lending: up 24%
- Capital city values, September quarter: down 4.3%
- Rents versus a year earlier: up 5.5%
- Trend dwelling approvals, August: 18,202 a month
The approvals gap that investors cannot close alone
The 24% rise in new-build lending only helps if projects actually start and finish. Trend approvals hit 18,202 in August. The 1.2 million homes target over five years needs roughly 20,000 a month. That is a shortfall of about 1,800 approvals a month, before counting any that stall between approval and completion.
Investor appetite for new stock is a useful input, but it is not the binding constraint. Planning, labour, materials and finance all sit ahead of it. Our guide to housing supply, approvals and building costs walks through where projects typically get stuck.
The awkward possibility is that policy nudges investors towards new builds faster than the industry can deliver them. Capital arrives early. Completed homes arrive late.
The case that weaker investing hurts renters
One chief economist argues that weaker investing starves an already tight rental market. The logic is straightforward. Roughly speaking, private investors supply most of Australia’s rentals. If fewer of them buy, and some exit, the stock of rentals grows more slowly than the number of people who need one.
The counterargument is also reasonable. Removing negative gearing on existing homes mainly dents the appeal of low-yielding, loss-making rentals. Those are the properties where an investor relies on tax offsets and capital growth rather than rent. Fewer of those might be a healthier mix over time, and falling prices plus rising rents improve the maths for the investors who stay.
Both things can be true. A tighter rental market in the near term, and a more yield-focused investor base in the medium term, are not contradictory.
What this means if you rent, own or invest
For renters, the next 12 months look like a seller’s market for landlords. Expect competition to stay high, particularly in the segments investors are least interested in buying into. Budgeting for continued rent rises is more sensible than hoping for relief.
For existing landlords, the pressure points are different. A property that relies on tax losses to make sense deserves a fresh stress test. One that earns a solid yield is better placed. If you are weighing a new-build purchase, build in time for delays and a holding cost before the first tenant arrives. Our look at property concentration risk is a useful reminder not to let one asset carry too much of your balance sheet.
For would-be buyers, softer values and a more selective investor crowd can mean less competition at the entry level. That is a possibility, not a promise, and it depends on your local market.
What could change this picture
Three things are worth watching. First, whether new-build lending keeps rising or fades once the initial reaction to the policy change passes. Second, whether monthly approvals move closer to the 20,000 mark. Third, whether rents keep climbing or flatten as the new stock slowly arrives.
If approvals stay near 18,000 and rents keep rising, the policy’s side effect becomes clear: the investor shift redistributes where capital goes without delivering more homes fast enough. If approvals pick up, the shift looks more like a useful nudge.
The practical take: treat the 24% as a signal about direction, the 9% as a signal about caution, and the approvals number as the one that decides how this ends. Want the weekly read on rates, supply and policy? Subscribe to the Australian Property Review newsletter.
General info, not financial advice.