Many investors are asking the wrong question. They want to know whether to sell before the tax rules change. The better question is what a pre-2027 valuation will actually protect, and whether a rushed sale protects anything at all.
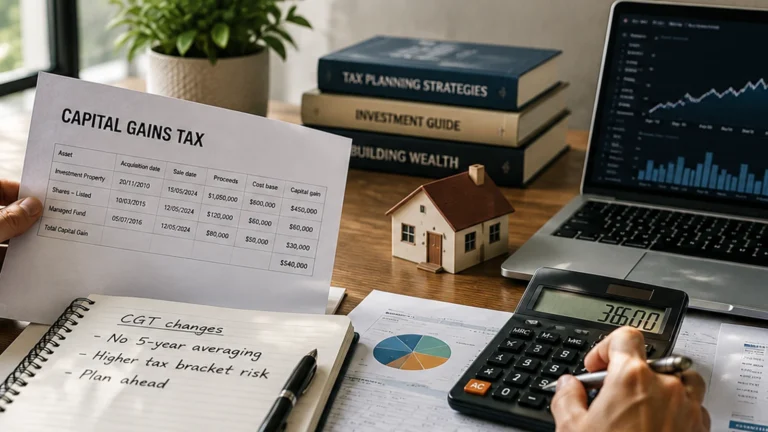
From 1 July 2027, the 50 per cent capital gains discount for resident individuals who hold an asset for at least a year is due to be replaced. The new setup uses an inflation-indexed cost base, plus a minimum tax of 30 per cent on real gains. Qualifying new residential builds are treated differently, because their owners can choose between the old and new systems.
That is the headline. The detail is where the decisions sit.
Why a CGT valuation before 2027 matters
The most important feature of the change is what it does not do. It is not retrospective. Gains built up before the start date keep the current treatment.
That is why a capital gains tax valuation around the changeover date carries weight. It draws a line between the gain that belongs to the old system and the gain that belongs to the new one. Without a credible figure on the day, that line gets argued about later, often when you are least able to prove anything.
In plain English: the valuation is the evidence. The sale is optional.
Key numbers
- 1 July 2027: the start date for the revised capital gains settings
- 50 per cent: the current discount for resident individuals holding at least a year
- 30 per cent: the proposed floor on tax applied to real gains
- 12 May 2026: the Federal Budget evening that set the negative gearing cut-off
A $1.2 million example, and why early sales often disappoint
Take a property bought 15 years ago for $500,000 and now valued at about $1.2 million. A large share of that gain was built long before 2027. Under a no-retrospective rule, that share keeps the existing discount whether you sell this year or hold on.
So what does selling early buy you? Often very little, and it costs real money to do it:
- Agent fees and marketing
- Stamp duty on whatever you buy next
- Borrowing costs on a new loan
- Time out of the market while capital sits uninvested
Those costs are certain. The tax saving is not. If most of your gain is already protected, a hurried sale swaps a protected position for a known bill. That is the catch.
Who is genuinely better off holding, and who might sell
Holding tends to suit investors with a long-held, strongly geared-down asset who plan to keep it for years. Their pre-2027 gain is already locked to the old treatment, and the new rules mainly affect gains from here on.
Selling can still make sense, but for ordinary reasons rather than tax panic. The asset may be underperforming. Your cash flow may be stretched. The property might not fit the portfolio any more. Those reasons existed before the announcement and they are better guides than a deadline.
A rule of thumb: if the only reason to sell is the tax change, price out the full cost of selling and rebuying first. If the numbers are close, hold.
How the new-dwelling test shifts the calculus
Qualifying new residential builds get a choice between the old and new capital gains systems. That is a meaningful advantage, because the owner can pick whichever produces the smaller bill when the time comes.
The same logic applies to negative gearing. New builds remain eligible for full loss offsetting. Established homes are treated differently depending on when they were bought.
That tilts the maths towards new stock for investors who care about tax settings. It does not make a new build a good buy by default. Price, location, rental demand and build quality still decide the return, and a tax concession on a weak asset is still a weak asset.
The negative gearing cut-off has already passed
Established homes bought before the evening of 12 May 2026 keep full loss offsetting against wages. Later purchasers face limits, with unused losses carried forward rather than lost.
This is the part many buyers get wrong. That grandfathering date has already lapsed. Buying established stock now cannot preserve the old treatment, so any argument that you must buy before the deadline no longer applies.
For existing owners, the practical point is the reverse. If you hold an established property bought before the cut-off, selling it forfeits a concession you cannot get back. Weigh that before listing.
What could still shift the picture
Two things sit outside the tax rules. The first is the market itself. If prices soften, that can offset some of the value of lost concessions, or make a sale less attractive when you would be selling into weakness. The second is policy detail. Final legislation may differ from what is currently described, so any plan should allow for adjustments.
None of this is a reason to freeze. It is a reason to be specific. Judge each asset on its likely future return, your own cash flow and what a sensible price looks like today.
A short checklist before you act
- Get a credible valuation dated close to 1 July 2027 for any asset you intend to keep.
- Work out how much of your gain was built before the start date.
- Price a sale in full: fees, stamp duty on the next purchase, borrowing costs and idle capital.
- Check whether your property is established or a qualifying new build.
- Check whether you bought before or after the 12 May 2026 cut-off.
- Ask an adviser to model your own numbers before committing.
If you want a fuller walk-through of how these rules interact, start with our guide to negative gearing, CGT and investor tax. And if you are weighing whether this is part of a longer pullback, see our look at whether investors are exiting for structural or cyclical reasons.
The calm reading is that the rules reward preparation more than speed. Get the valuation. Run your own numbers. Then decide.
Subscribe to the newsletter for the weekly signal on tax, rates and policy.
General info, not financial advice.