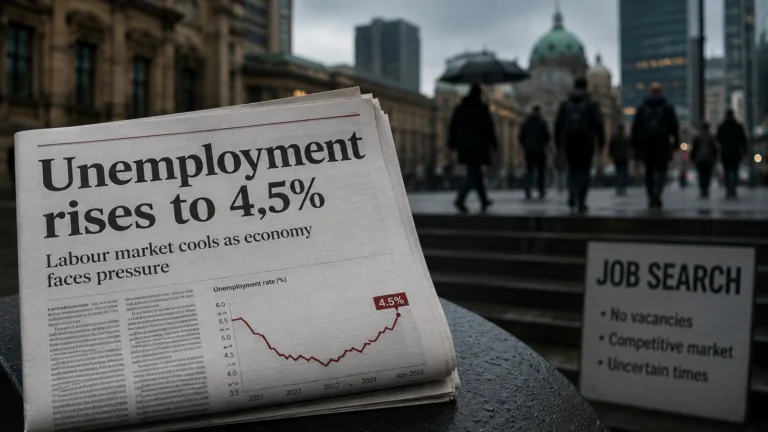
A household can be in monthly deficit for a long time without missing a single repayment. That gap between stress and default is the most important thing to understand about the latest quarterly mortgage stress study, which counts 450,539 households in the nation’s leading postcodes now spending more than they earn.
The count rose by 31,318 over the September quarter and is 79,072 higher than a year ago, a 21 per cent jump. Pressure increased in 61 of the 77 postcodes examined. The analyst behind the data calls it a tipping point and expects the next quarter to look worse. Take the forecast seriously, but read it carefully. A deficit is a cash-flow measurement, not a default count.
Why a deficit is not yet a default
Most households in deficit are covering the shortfall from somewhere. That might be savings, an offset balance, a second income, a credit card, or cutting discretionary spending. Each of those has a limit, and the limit is the real story. Default risk rises when the buffer runs out, not when the deficit first appears.
That is why the headline number tells you less than the trend in it. A rising count means more households are drawing down their cushions. It does not tell you how many cushions are close to empty. The data supplied does not say, so anyone claiming a precise default forecast is guessing.
Where the strain sits in Victoria and New South Wales
Victoria carries the largest load, with 104,325 stressed households across its top 10 postcodes, up 10,501 or 11.2 per cent in the quarter. Roxburgh Park (3064) leads with 13,624 households, which is 53 per cent of the total there. In New South Wales the figure is 94,459, up 5,923 or about 6.7 per cent. Liverpool leads with 15,553, and Blacktown’s stress count climbed 33.5 per cent.
For anyone searching for Sydney and Melbourne mortgage stress, the pattern is outer-suburban. These are areas where many buyers stretched to enter the market and carry large loans relative to income. Our earlier look at who is squeezed by suburban rate rises in Sydney and Melbourne covers the serviceability mechanics behind that.
The surprise: stress is climbing in richer areas too
The analyst notes that wealthier postcodes are increasingly affected. The logic is simple. Bigger incomes support bigger mortgages, so a rate rise hits a large loan hard even when the household earns well. High earners often have more room to cut spending, but they also tend to have more leverage.
The regional picture shows how uneven the pressure is. Manunda in Cairns jumped 156 per cent, from roughly 2,200 to about 5,600 households. Toowoomba has 14,853 stressed households. State-level rises over the quarter ranged from 3.5 per cent in South Australia to 13.7 per cent in Tasmania, with Queensland at 9.1 per cent and Western Australia at 5.5 per cent.
The catch: the data cannot tell us who is exposed by loan type
Here is the limit of the study. It counts households in deficit by postcode. It does not break the group into recent buyers, investors, or those rolling off fixed rates, so those groups are the obvious places to look rather than confirmed findings. Recent buyers usually have the thinnest equity and the least time to build savings. Investors face a mix of repayments and rental income that can swing either way. Anyone coming off a low fixed rate faces a repayment step-up they may not have fully budgeted for.
The drivers named in the study are high interest rates, inflation, stagnant real incomes and a September rate rise from the central bank. Those pressures stack. For more on how the rate path is shaping winners and losers, see who benefits from higher interest rates as the RBA keeps hiking.
What would change the picture
Three things matter most over the next few months:
- Rates. Another rise would push more households across the line. A pause would slow the count but not reverse it quickly.
- Incomes. Real wage growth would ease the squeeze. Stagnant incomes keep it going.
- Lender behaviour. Hardship arrangements can delay defaults, but they defer the problem rather than solve it.
If you are a borrower, the practical test is simple. Work out how many months of repayments you could cover from savings and offset funds if income dipped or rates rose again. If the answer is under three, talk to your lender about hardship options early, before a missed payment, not after. Our guide to mortgage stress and arrears lays out the steps.
Want the weekly signal on rates and credit? Subscribe to the newsletter.
General info, not financial advice.