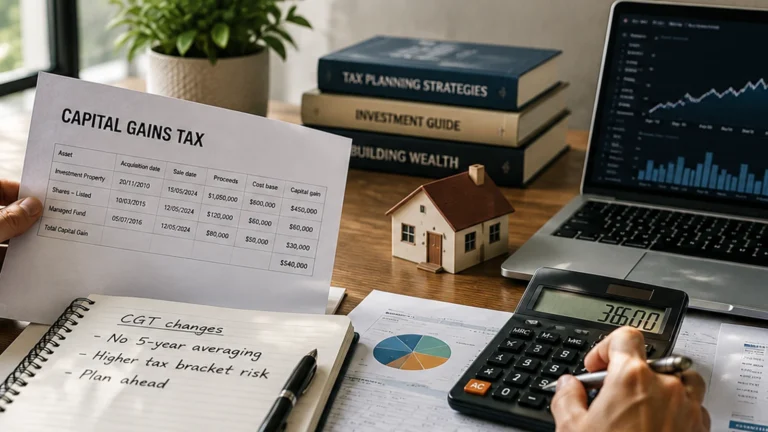
The federal government’s proposed trust distribution tax creates a structural problem for property investors: a change to how trust income is taxed at Commonwealth level, with no indication states will adjust their own stamp duty calculations in response. The gap between the two systems means investors could face dual exposure, once when the trust rule changes hit, again if states treat any resulting restructure as a dutiable event.
The mechanics matter because many property investors hold assets inside discretionary trusts for asset protection and succession planning. The federal measure targets how distributions from those trusts are taxed, tightening rules around income splitting. That’s a cash-flow issue for some investors. The structural risk sits one layer deeper: if an investor needs to restructure to reduce the new tax burden, moving property out of a trust and into personal or company ownership can trigger state stamp duty, even though the beneficial owner hasn’t changed.
Why states haven’t moved
Stamp duty is a state revenue line. NSW collected $9.4 billion in transfer duty in 2023-24, Victoria $8.1 billion. Any concession or exemption for trust restructures would hit those budgets directly. State treasuries have not announced relief measures, and the federal proposal did not include compensation to offset any state revenue loss from coordination.
The result: silence from state governments does not mean the issue is being worked through behind the scenes. It means investors planning restructures should assume full stamp duty applies unless a specific exemption is legislated before the federal changes take effect.
The catch for NSW and Victoria holdings
Property investors with assets in NSW and Victoria face the highest exposure. NSW charges stamp duty on the full dutiable value, no threshold relief for high-value transfers. Victoria applies a progressive scale with an additional surcharge for trusts acquiring property. Both states have history declining to coordinate with federal tax changes when it would cost revenue.
An investor holding a $2 million Sydney property in a discretionary trust who restructures to personal ownership would face approximately $82,000 in NSW stamp duty. In Victoria, a comparable $1.5 million Melbourne property would trigger roughly $82,000 in duty. Those are sunk costs with no tax deduction, paid purely to move an asset from one structure you control to another structure you control.
The numbers
- NSW stamp duty on $2 million property transfer: ~$82,000
- Victoria stamp duty on $1.5 million transfer: ~$82,000
- Federal trust tax implementation: expected 2025-26 financial year
- State coordination announcements to date: zero
- Investor holdings in discretionary trusts (ATO data, 2022): 34% of all rental property ownership structures
Which restructuring options remain
Investors have three paths before the federal change lands, each with trade-offs:
-
Do nothing and absorb the federal tax hit. Simplest option if the new trust distribution rules only marginally increase your tax relative to the cost of restructuring. Requires modelling your specific trust distributions and beneficiary tax rates.
-
Restructure now and pay stamp duty. Moves the asset to a lower-tax structure before the federal rules apply, but locks in the state duty cost immediately. Only makes sense if the present value of future federal tax savings exceeds the upfront duty plus the cost of lost flexibility (trusts allow income splitting and asset protection that personal ownership does not).
-
Wait for state announcements and accept the risk. Assumes states may still introduce relief measures closer to the federal implementation date. The risk: they don’t, and by the time that’s confirmed, you’re restructuring in a rush with less time to optimise the new structure.
None of these are clear wins. The decision depends on your current trust distributions, your beneficiaries’ marginal tax rates, the dutiable value of your holdings, and how much you value the non-tax benefits of the trust structure.
Red flags in the next six months
Three things would change the equation:
-
State budget updates (mid-2025) with no mention of trust restructure relief. That’s the clearest signal states are not moving. NSW and Victoria both deliver budgets in June; if trust duty exemptions aren’t flagged there, assume they’re not coming.
-
ATO guidance on what constitutes a restructure for stamp duty purposes. The federal tax office has no jurisdiction over state duties, but if they publish detailed examples of how the trust tax applies, state revenue offices may respond with their own guidance on whether certain restructures are dutiable. Watch for that.
-
Investor restructure volume spiking before the federal effective date. If enough investors move early, states face political pressure to introduce relief, or they pocket a windfall from rushed restructures. Either outcome tells you something about the coordination gap.
What property investors should do now
Model it before you move. Get your accountant to calculate:
- Your current trust distributions and tax paid under existing rules
- Your tax under the proposed federal trust changes, assuming you keep the current structure
- Your tax if you restructure to personal or company ownership, including the upfront stamp duty cost and any loss of income-splitting benefit
Then compare the net present value over a realistic hold period, 10 years if you’re a long-term investor, five if you’re closer to exit. The answer will be different for a single-property investor with one beneficiary versus a multi-property investor distributing to adult children in lower tax brackets.
Do not restructure purely because the trust tax is changing. Restructure only if the numbers show a clear saving after accounting for stamp duty, legal costs, and the non-tax benefits you lose. And do not assume state relief is coming, hope is not a strategy when the cost of being wrong is five figures in sunk duty.
For context on how investor behaviour shifts under policy pressure, see Victoria investor exodus doubles: landlord sales outpace buyers two-to-one. The trust tax change is different in kind (it’s a restructure decision, not a sell decision), but the pattern holds: when policy creates uncertainty and states don’t coordinate, investors either pay the cost or exit the position.
Base case: states do not move
The most likely scenario is states take no action before the federal trust tax applies. That means:
- Investors who restructure will pay full stamp duty in NSW, Victoria and other high-duty states
- Investors who don’t restructure will absorb the higher federal tax from 2025-26 onward
- The coordination gap becomes a permanent feature, not a transitional issue
The upside scenario, states introduce targeted relief for trust-to-personal transfers where beneficial ownership is unchanged, requires legislative action in at least NSW and Victoria. No draft bills are public, no treasurer has flagged it in recent statements, and state revenue offices have not issued guidance.
That does not make relief impossible. But if you are making a restructure decision in the next six months, the safe assumption is you will pay full duty.
Subscribe to the newsletter for updates when state budgets drop and when federal implementation details are finalised.
General info, not financial advice.