A cash rate hold at 4.6% through December is now a mainstream forecast. A chief economist at a regional lender expects the Reserve Bank to pause after the fourth hike in eight months. But a hold is not a cut, and the evidence suggests borrowers should not read it as the start of relief.
What changed and what didn’t
The cash rate is at its highest level since 2011. The economist’s call is that the RBA stays put for the rest of the year. Nothing in that forecast points to cuts. He has been explicit that the bank wants consumer price inflation back below 3% sometime in 2027, which is a long way off.
So the headline is a pause, and the fine print is a long plateau.
Key numbers
- Cash rate: 4.6%, the highest since 2011
- Hikes: four in eight months
- Inflation target in this forecast: below 3% sometime in 2027
- Households expecting higher mortgage rates: just over 80%, up from 63% in September
- Another view: a rise at the 2-3 November meeting, with standard variable rates above 9%
Why a hold is not the same as relief
The economist’s reasoning leans on pressures that do not fade quickly. Oil is expensive and diesel is at record highs. The jobs market is tight, government spending is heavy and productivity is sluggish. On top of that, a global surge in technology investment has companies and governments competing for the same labour and funding.
None of that is solved by a pause in rate rises. It is the backdrop that keeps the RBA cautious about cutting even if it stops hiking. Put simply, the hold is a ceiling that stays in place, not a floor that lets borrowers breathe.
Where commentary splits
Commentary on this forecast has split along predictable lines. One camp treats the hold as the sensible central case, given how much damage the earlier hikes are doing to households. Another camp is not convinced the tightening is finished and expects one more rise in early November, which would push standard variable rates above 9%, a level not seen since 2008.
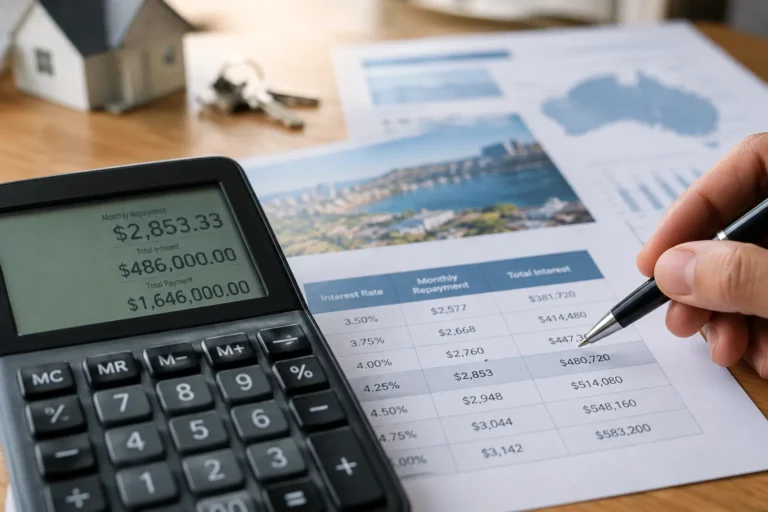
Both views can be partly right. A hold at 4.6% and a 9% variable rate are not far apart in what they mean for a stretched borrower. Either way, repayments stay painful for a long time.
Testing the forecast against sentiment and pricing
Consumer sentiment has fallen more than 12% in a year. Spending has stalled. Fuel excise relief lapsed in August, so costs are rising just as household budgets are tightening. And more than 80% of respondents now expect mortgage rates to climb further, against 63% in September.
That last number matters. Households do not expect a hold. If borrowers and fixed-rate lenders both price in more rises, the market is leaning against the forecast. Fixed-rate pricing is the cleanest read on that expectation, though the figures supplied here do not include current fixed rates, so treat any comparison as directional rather than exact. The direction is what counts: if expectations keep running ahead of the forecast, a hold is the optimistic case.
For more on how repayments respond to rate moves, see our guide to RBA rate decisions and mortgage repayments.
How long a plateau takes to reach property prices
Property values are already easing, but a plateau in the cash rate does not stabilise prices on its own. Three lags are worth separating.
- Repayment lag. Borrowers on variable loans have already absorbed the hikes. Those rolling off fixed rates are still facing higher repayments, so the squeeze can keep building after the RBA stops moving.
- Sentiment lag. Confidence tends to recover after rates fall, not when they stop rising. With the target for inflation set for 2027, buyers have little reason to rush back.
- Supply lag. Sellers who are not forced to sell often wait. That can slow price falls, but it also keeps transaction volumes thin and discovery of the true price slower.
In practice, a plateau tends to produce a drawn-out, uneven stabilisation, not a clean floor. Regional markets that ran hardest, such as the surge covered in our look at regional Victoria’s price run, are the ones most exposed to a sentiment-led slowdown. Better-supported pockets may hold up longer. Our take on secondary cities in the next cycle covers where that resilience may sit.
What could derail the hold
The forecast has clear weak points. Oil and diesel could rise further. A tight jobs market could keep inflation sticky. A weaker Australian dollar, now under 70 US cents, adds to imported costs. Any of these could push the RBA back into hiking mode.
On the other side, stalled spending and falling confidence could cool demand faster than expected, making a longer hold more likely. Equities hitting records also complicate the picture, since wealth effects can prop up spending among higher-income households.
Budget for a long plateau, not a pivot
Plan around a long plateau, not a quick pivot. That means stress-testing your budget at a higher rate than today’s, keeping a cashflow buffer, and not assuming a pause means prices have found a floor. If you are weighing a purchase or a refinance, build the decision around what you can carry if rates stay here, or edge higher, through 2027.
For weekly analysis like this, subscribe to the newsletter.
General info, not financial advice.