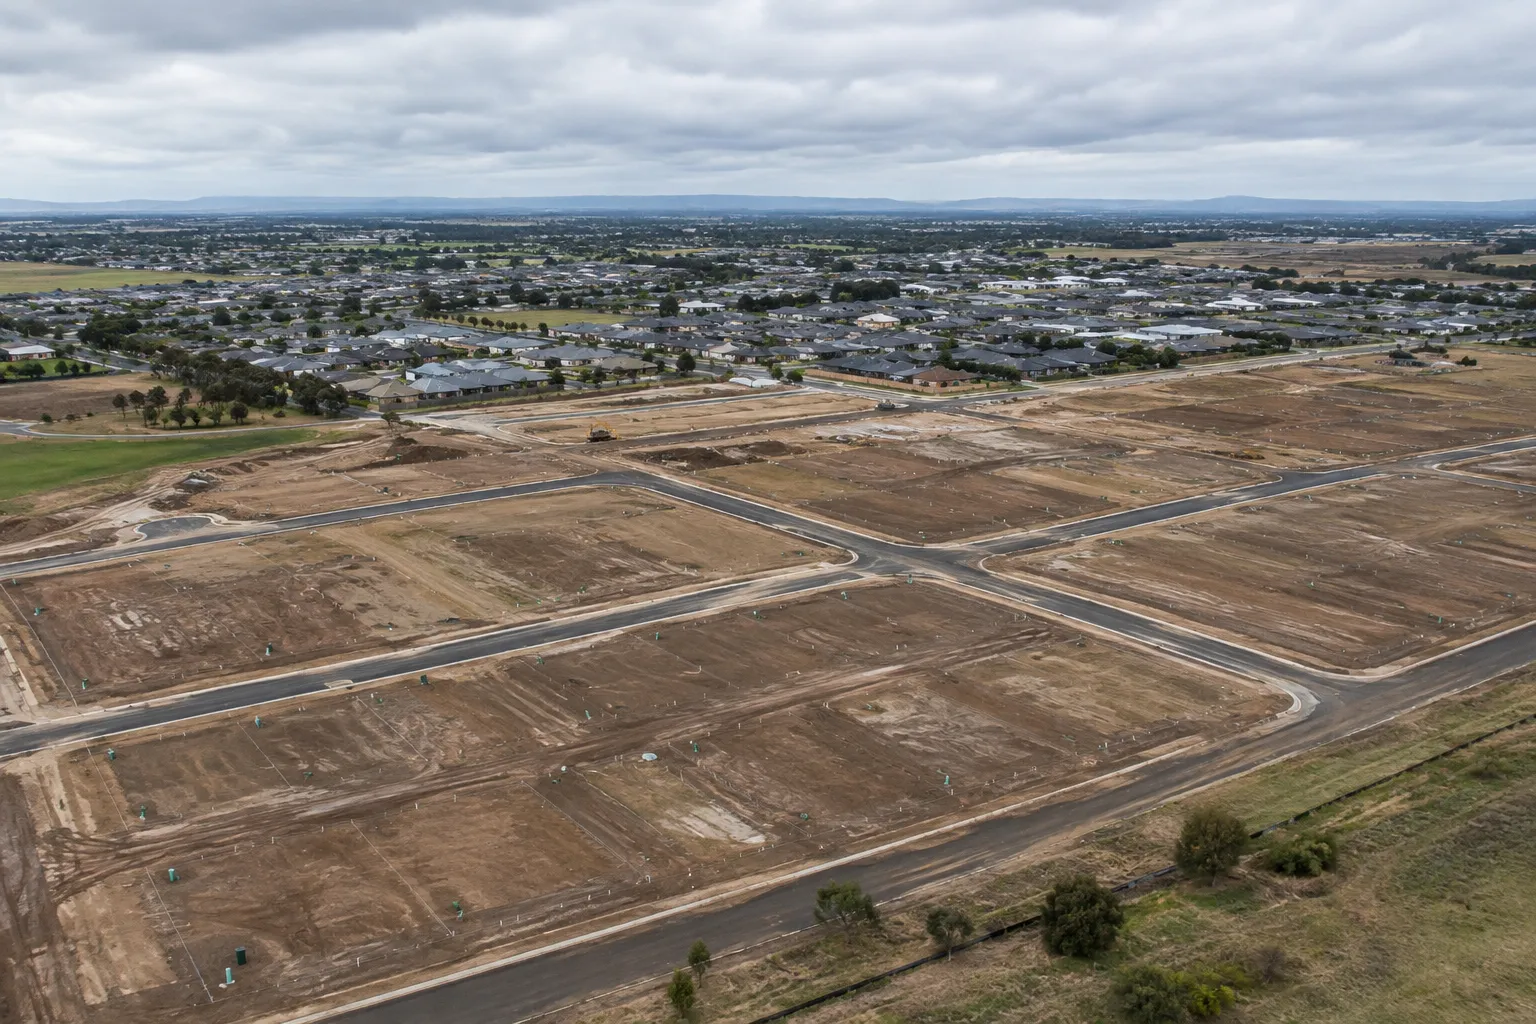
A major residential developer has committed $115 million to acquire land in Melbourne’s outer suburbs at a moment when the city’s housing market is contracting, construction costs remain stubbornly high, and the private credit sector is rationing capital. The deal raises a blunt question: does this reflect genuine confidence in Melbourne’s medium-term housing demand, or is it a response to government volume-housing targets that may not align with project economics?
Melbourne’s median house price has fallen 4.2% over the past twelve months, the sharpest decline of any capital city. Apartment markets are softer still. At the same time, wage growth is running below inflation, migration inflows have moderated, and borrowing capacity has contracted as interest rates hold above 6%. Developers ordinarily retreat from land acquisition during this kind of cycle.
Why land now
Three factors explain the timing. First, the Victorian government has set ambitious dwelling targets tied to infrastructure funding and planning approvals, developers who can demonstrate land holdings and capacity may gain access to faster approval pathways and rezoning concessions. Second, land prices in growth corridors have softened enough that well-capitalised buyers see a margin opportunity if construction costs normalise over the next 24 months. Third, developers with strong balance sheets are positioning for the recovery phase, betting that current weakness creates a competitive advantage over rivals locked out by credit constraints.
The risk is that construction cost relief takes longer than expected, or that demand remains weak enough to erode returns even if land was bought at a discount.
The viability gap
Building a detached house in Melbourne’s outer suburbs now costs between $2,800 and $3,400 per square metre, depending on finishes and site conditions. That puts a standard 200-square-metre home at $560,000 to $680,000 in hard costs alone, before land, holding costs, marketing, and developer margin. Land in growth corridors typically adds another $200,000 to $350,000 per lot after subdivision and infrastructure contributions.
For a project to clear a 15% return, the threshold most institutional capital requires, the end sale price needs to sit above $950,000. That’s within reach in some pockets, but it’s tight. If buyer appetite weakens further or if lenders tighten serviceability, that margin collapses.
The catch
Construction cost assumptions baked into land deals today rely on labour and materials easing over the next two years. If skilled labour shortages persist or if supply chain disruptions return, those costs could stay elevated or rise further, turning a calculated land bet into a margin squeeze.
Who’s still funding this
Private credit funds, which underwrote a significant share of residential land deals between 2021 and 2023, have pulled back sharply. Several major funds have gated redemptions or stopped new originations entirely as valuations lag market reality and as interest rate risk compounds.
Developers with access to balance-sheet equity or institutional joint-venture partners are now the only buyers moving at scale. That leaves smaller operators frozen out, which reduces competition for land but also signals that the broader market sees more risk than opportunity right now.
Scenarios over the next 12 months
Base case: Melbourne prices stabilise but don’t recover meaningfully. Construction costs ease 5% to 8% as residential building activity slows and subcontractor availability improves. Land bought today breaks even or delivers a low-teens return if sold into the market in 2028.
Upside: Interest rate cuts arrive sooner than expected, buyer confidence returns, and prices lift 6% to 10% by late 2027. Early land acquisitions capture that uplift and deliver returns above 18%.
Downside: Demand stays weak, construction costs hold or rise, and project economics don’t stack up. Land sits undeveloped or sells at a loss. Developers who stretched balance sheets to acquire land face refinancing pressure if holding costs compound.
What it signals
Large-scale land acquisitions during a down cycle are either contrarian intelligence or forced moves driven by policy settings rather than market fundamentals. In this case, the deal size and location suggest the buyer is banking on government infrastructure commitments and population growth assumptions that may take five to seven years to materialise.
That’s a long holding period with meaningful execution risk. If migration settings shift again, or if infrastructure timelines blow out, the land could sit unproductive while carrying costs accumulate.
Practical take for anyone tracking Melbourne supply
Watch three things over the next six months. First, whether other large developers follow with similar acquisitions, one deal is a data point, a pattern is a signal. Second, construction cost trends: if quotes start falling materially, it validates the land-now thesis. Third, approval timelines: if the government accelerates planning pathways for land already banked, it confirms that policy settings are shaping decisions more than market fundamentals.
If you’re an investor or upgrader watching Melbourne’s outer suburbs, don’t interpret this deal as evidence that prices are about to recover. It’s a medium-term bet on structural settings, not a signal that buyer demand is about to rebound.
Subscribe to the newsletter for weekly breakdowns of what’s actually moving the market.
General info, not financial advice.