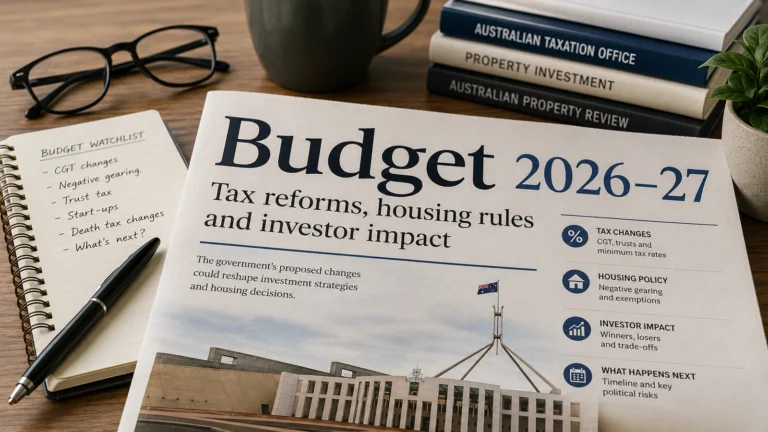
How does negative gearing work in Australia? For four decades the answer was simple: if your rent didn’t cover your costs, the shortfall came off your taxable salary. After the 12 May 2026 federal budget, the answer now depends on when you bought and what you bought. That makes it one of the biggest shifts in investor tax in a generation.
How the old deduction actually works
Negative gearing means the costs of holding a rental, mainly loan interest, exceed the rent you collect. The loss is not wasted. It reduces your other taxable income, usually wages, so you pay less tax.
A worked case shows why the strategy is a bet on price growth and not a free lunch. Consider an investor on $110,000 a year who buys a $750,000 unit, borrows $600,000 at 6.1% and collects $650 a week in rent. The tax loss comes to $17,800. That produces a refund of $5,696. The owner still wears roughly $6,100 a year, or about $117 a week, out of pocket.
The refund softens the loss. It doesn’t erase it. The investor is paying that gap in the hope that capital growth more than covers it.
The date test: 30 June 2027
The budget did not scrap the deduction outright. It split investors into groups based on timing and property type.
For established properties bought after the budget announcement, losses can still offset salary only until 30 June 2027. From 1 July 2027, those losses are ring-fenced. They can be used against residential rental income or against the eventual sale gain, and any unused amount carries forward.
In practice, that changes the cashflow maths. A loss that used to arrive as a tax refund each year now becomes a credit you may not use until you sell or until your rent rises.
New builds sit outside the squeeze
New builds, including apartments and house-and-land packages, are exempt from the ring-fencing. That is a deliberate nudge toward adding supply. However, there is a catch. Knocking down and rebuilding one house is not treated as a new build.
Key numbers
- $17,800: tax loss in the worked example
- $5,696: the tax refund
- About $117 a week: the investor’s real cost after the refund
- 1 July 2027: ring-fencing starts for established property
That box sums up the new tension. A tax break that costs the owner $117 a week is only worth holding if you can use the losses efficiently.
Capital gains: indexation replaces the discount
The other half of the package covers the sale. Gains that build up after 1 July 2027 on assets that are not new builds move to inflation indexation, taxed at a minimum of 30%. Investors who relied on a flat discount should model both rules before they buy or sell, because the break-even point shifts.
Our own negative gearing, CGT and investor tax guide covers the mechanics, and the capital gains tax valuation deadline piece explains why timing matters for existing holdings.
What it means for different readers
- Existing investors: check which side of the date each property sits on. A holding bought before the cut-off may keep its current treatment, but confirm that with an accountant and not a guess.
- Would-be investors in established stock: rental yield and your cash buffer matter more now, because the salary offset is time-limited.
- Buyers eyeing new builds: the exemption is real, but it does not make a poor property a good one. Price, location and tenant demand still decide the outcome.
- First-home buyers: less investor appetite for established homes could ease competition at the margin, though the size of that effect is uncertain.
The risk nobody can price yet
The unknown is behaviour. Tax changes alter incentives, but investors also react to rates, vacancy and confidence. We have already written on investor confidence as a systemic risk, and this reform adds another variable to it. How many investors shift to new builds, and whether that adds supply fast enough, remains to be seen.
The next step is simple. Before you buy or sell an investment property, run your numbers under both the old and new rules, then talk to a tax adviser about your own situation. If you want the weekly signal on policy moves like this, subscribe to the newsletter.
General info, not financial advice.