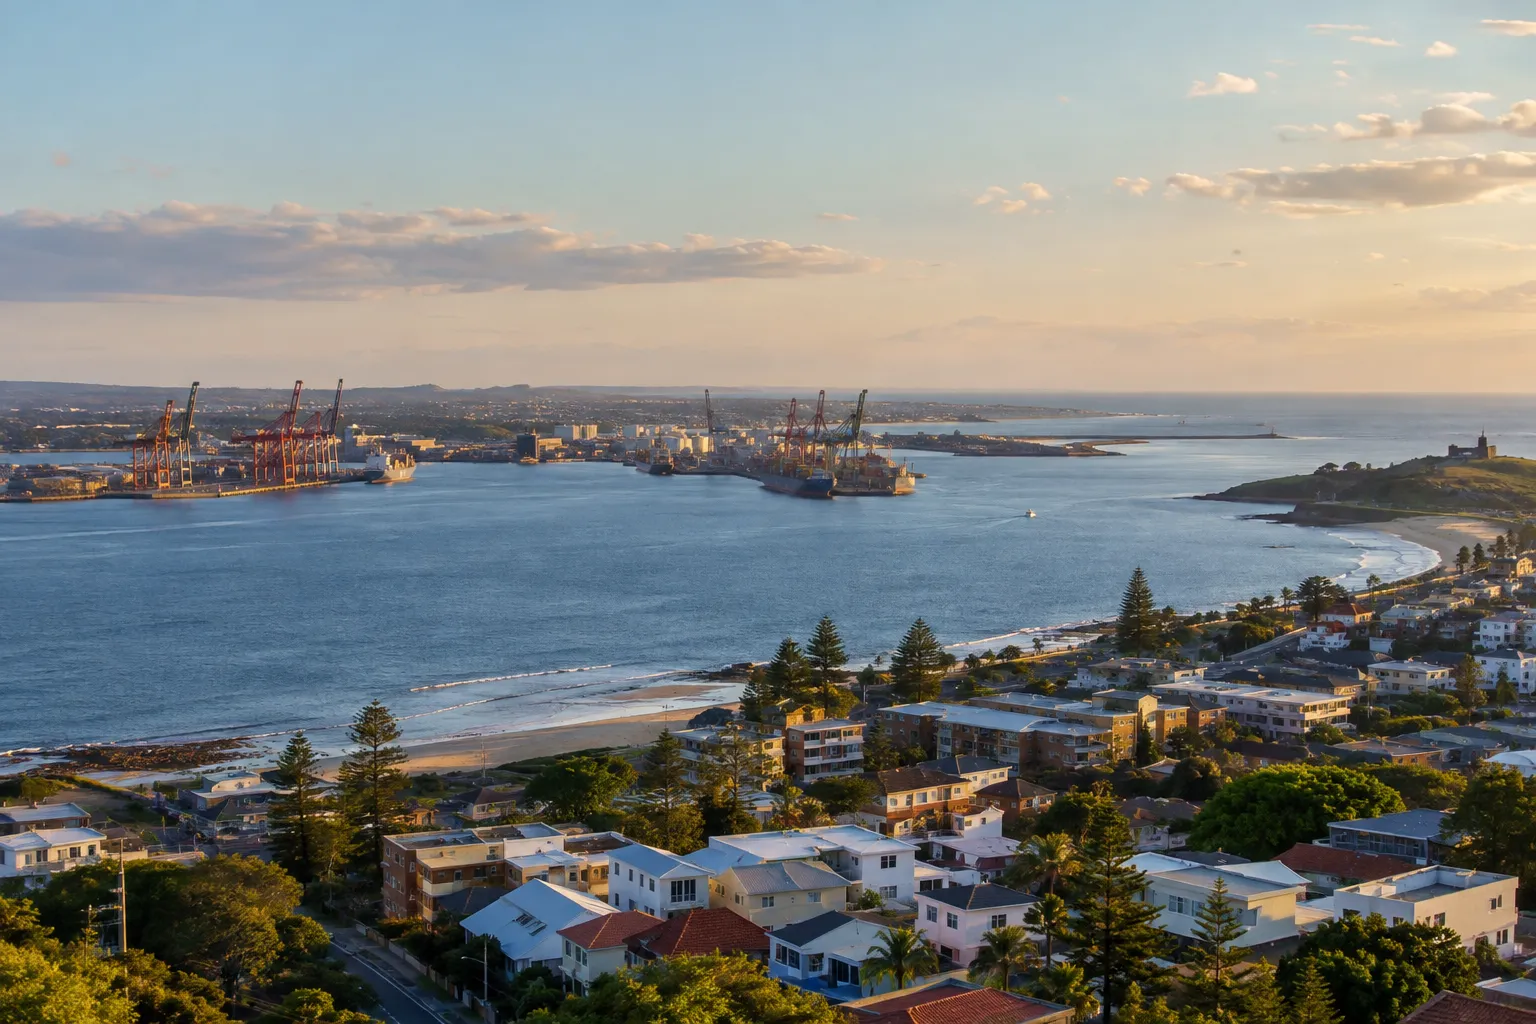
Two numbers from the Hunter Region point in opposite directions. Some pockets around Newcastle and Lake Macquarie have reportedly fallen by as much as 10 per cent. Yet Cotality data shows the Lower Hunter median up 9.3 per cent over the past year, to $785,985. Both can be true at once, and the gap between them is the story.
The short version: the annual figures look back, the price falls look forward. Newcastle property prices are now reacting to a change in who is buying, not to a change in how many people want to live there.
Two numbers, one market
A 12-month median captures a year of sales, most of which settled before the shock. A sharp drop in recent contracts takes months to drag that average down. So a rising annual median does not rule out a soft patch in the latest weeks. It mostly tells you where prices were, not where they are heading.
The Upper Hunter shows the same pattern. Its median is up 9 per cent to $585,556 over the year. Neither figure says anything about current momentum.
The buyers who stepped back
Local buyer’s agents point to Sydney-based investors, often called rentvestors. These are people priced out of their home city who buy elsewhere, rent the property out, and may move or work remotely later. They are leveraged buyers, so they are sensitive to tax settings.
According to those agents, the federal government’s May tax changes removed deduction benefits on established properties. Prices then reportedly fell 5 to 10 per cent in the affected segments. Maitland, a first-home-buyer favourite about 35km north-west of Newcastle, is down roughly 5 per cent. Homes in the $3 million to $5 million-plus bracket have also weakened.
The detail worth noting is that this is demand from outside the region. Local wages and local jobs did not change in May. The marginal buyer did.
Quick take
- Up to 10 per cent: reported falls in parts of the Hunter
- 5 to 10 per cent: reported drop after the tax announcement
- 9.3 per cent: Lower Hunter annual median growth (Cotality), to $785,985
- $17 billion: committed capital announced in six weeks of mid-2026
The catch with metropolitan money
Regional markets that lean on outside investors carry a hidden dependency. When tax or credit conditions change in Sydney, the effect shows up in Newcastle without any local trigger. That is the catch for anyone reading a strong annual median as proof of independent strength.
It also explains why the weakness is uneven. Not every buyer type is leaving.
Who is still buying
Downsizers remain active, especially for single-level, renovated homes close to shops. Agents name New Lambton, Warners Bay, Eleebana and Valentine as the places where that demand holds up. These buyers usually have equity from a prior sale and are less exposed to investor tax rules. Their presence puts a floor under part of the market, though not the segments rentvestors favoured.
Can the infrastructure pipeline fill the gap?
A developer cited more than $17 billion of committed capital announced over six weeks of mid-2026. The projects include rail manufacturing, pumped hydro, Greensteel and a Lockheed Martin defence precinct. Its managing director calls the slowdown a short-term bump, expects a very different market within two to three years, and says rents remain extraordinarily strong.
That is an interested view, and the timing deserves scrutiny. Announced capital is not the same as hired workers. Construction phases bring tradies first, permanent roles later, and each stage has its own housing demand. A pipeline of this size can lift owner-occupier demand, which is steadier than investor demand. But it arrives over years, while a leveraged investor can exit in a month.
Scenarios to hold in mind
- Base case: investor demand stays subdued, downsizers and local buyers absorb stock, and prices drift or plateau in the weaker segments while stronger suburbs hold.
- Upside: infrastructure employment lifts local owner-occupier demand faster than expected, and the softness proves brief.
- Downside: the pipeline slips or hires slowly, and the investor pullback spreads into the segments that have so far held up.
Strong rents help the case for the pipeline, but they do not offset a tax change that reduced after-tax returns for the buyers who were propping up price growth.
What it means for you
If you own in the Hunter, the annual median is not a guide to what your property would fetch this month. Check recent comparable sales in your own suburb rather than the headline growth figure. If you are an investor, test your numbers against the new tax treatment before assuming the old yield maths still applies. If you are a buyer, softer segments may offer negotiating room, but a recovery depends on assumptions about jobs and construction that nobody can guarantee.
For wider context on how downturns and clearance rates behave, see our guide to house prices, downturns and auctions. The same logic applies here: look at the most recent sales, not the trailing average.
Start here: pull recent sold prices for your target suburb and compare them with the 12-month median before you commit.
If you want the weekly signal, subscribe to the Australian Property Review newsletter.
General info, not financial advice.