Two investors each have $800,000 to deploy. One buys an established townhouse. The other buys a new one. Under the changes reported from the May 2026 Budget, only one of them keeps the old tax settings. That gap is now baked into the price of every new dwelling an investor looks at.
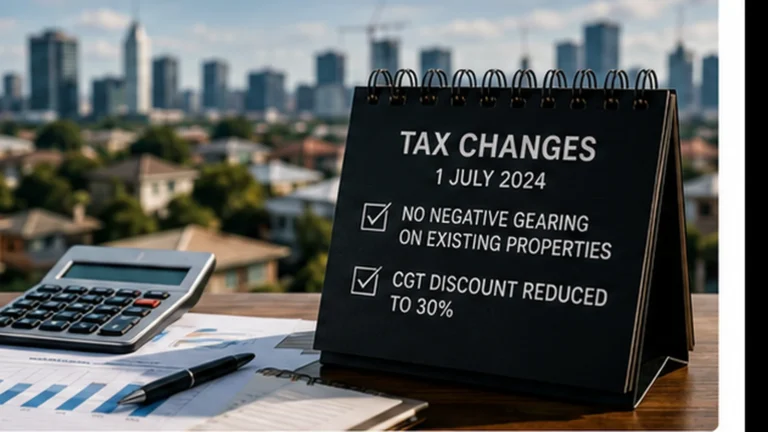
The reported changes are simple to state. Negative gearing has been removed for established investment properties bought after budget night. The 50% capital gains discount is being replaced by an inflation-indexation approach for those same assets. New builds are carved out of both. They keep the discount and keep negative gearing. They also keep depreciation and capital works deductions.
The after-tax gap, in rough terms
Think of it as a sliding scale rather than a fixed number. The size of the advantage depends on three things: how long you hold, how fast the property grows, and your marginal tax rate.
- Short hold, low growth: The difference is modest. Losses on an established property matter most in the early years, so the early cashflow hit is the main cost.
- Long hold, strong growth: The difference widens. A 50% discount on a large gain beats indexation by a lot, because indexation only credits you for inflation, not real growth.
- High marginal rate: Everything above is amplified. The higher your tax bracket, the more each deduction and each discounted dollar of gain is worth.
The catch is that the gap is only real if the new build actually grows at a comparable pace. A tax advantage on an asset that underperforms is not an advantage.
Key numbers
- Capital gains discount: 50% for new builds, indexation for established stock bought after budget night
- Negative gearing: retained for new builds, removed for post-budget established purchases
- Depreciation and capital works deductions: still available on new dwellings
Does this add homes, or just move demand?
This is the question that matters for policy. A tax incentive that points investors at new dwellings is only a supply win if it causes extra construction that would not otherwise have happened.
There are two ways it can go. In the good version, investor demand gives builders and developers the confidence to start more projects. More homes arrive, and renters benefit. In the weaker version, the same pool of new stock gets more contested. Investors bid against first-home buyers and upgraders for the same finite number of completions, and the extra demand shows up as higher prices rather than more bricks.
Which version we get depends on how quickly construction can respond. If land, labour, materials and approvals are tight, supply cannot flex fast. Demand then does the work on prices instead. That is the pattern worth watching in house-and-land packages and off-the-plan stock over the next few quarters.
Who gets squeezed
Owner-occupiers hunting for a new home are the obvious losers if investors crowd in. They do not get the same tax benefits, and they are bidding against buyers who do. First-home buyers in growth corridors are the most exposed, because that is where new-build supply is concentrated.
Existing investors face a different problem. Anyone holding established stock now owns an asset that is harder for the next investor to justify buying. That can weigh on resale demand. It also helps explain why some landlords are already reconsidering whether to hold, as we covered in Melbourne property investors are quitting rentals fast.
The part the tax maths leaves out
Tax treatment is one input. It is not the whole return. New builds in emerging areas can carry thinner rental demand, longer vacancy while a suburb matures, and a risk of oversupply when many dwellings complete at once. A first-year premium over comparable established stock is also common, and that premium eats into the tax benefit.
Warranties and lower early maintenance are genuine positives. But they are a cost-smoothing benefit, not a growth driver. An investor who overpays for a new build and then sits through a soft rental market can lose more than the tax regime ever gave back.
There is also a policy-delivery risk. Incentives only turn into homes if planning and approvals keep pace, which is a live issue in several states. Our look at WA planning reforms and the real bottleneck shows how funding alone does not clear a pipeline.
What would change my mind
Three signals would tell us the policy is genuinely adding supply:
- Building approvals and commencements rising in the regions where investors are most active.
- New-build price growth that does not outrun established stock by a wide margin.
- Rental vacancy staying tight as new dwellings complete, which would show real absorption.
If instead new-build prices climb faster than approvals, that points to demand being redirected rather than supply being created.
Bottom line
The tax gap between new and established dwellings is real and, for a long-hold investor in a growth market, potentially large. But a tax edge is not a reason to buy on its own. Price, location, target tenant and a cashflow buffer still decide the outcome. Before committing, ask a broker or accountant to model both options after tax, using your own rate and a realistic growth range rather than a best case.
Want the weekly signal on policy and property? Subscribe to the newsletter.
General info, not financial advice.