Every tax rule that draws a line eventually bends behaviour around that line. The Federal Government’s negative gearing overhaul follows the same pattern, and the boundary it has set turns on what counts as a “new” residential dwelling. Who falls on the right side of that definition keeps a valuable deduction. Who does not, loses it.
The rules are still moving. The reforms are arriving in three legislative steps, and the October bill is now with the Senate Economics Legislation Committee, due to report on 13 November 2026. That timing matters, because the definition could still change at the margins before it settles.
The line that now separates two kinds of investor
The June instalment sorted investors by timing. Anyone holding a residential interest before 12 May 2026, Budget night, keeps access. Anyone buying later has to show the property meets the statutory test for a new dwelling.
An August amendment, Schedule 4, patched the most awkward edge of that rule. It covers survivors, co-owners and separating spouses who would otherwise have been caught by the acquisition-date test, a problem the Coalition labelled the “widow’s tax”. The fix shows how quickly a clean-looking date can produce messy human outcomes.
Self-managed super funds face a separate hurdle. From 10 August 2026 they cannot enter fresh limited recourse loans for residential property. Existing loans and rentals are untouched.
Four routes in, and what each one rewards
The October bill lists four ways a property can qualify:
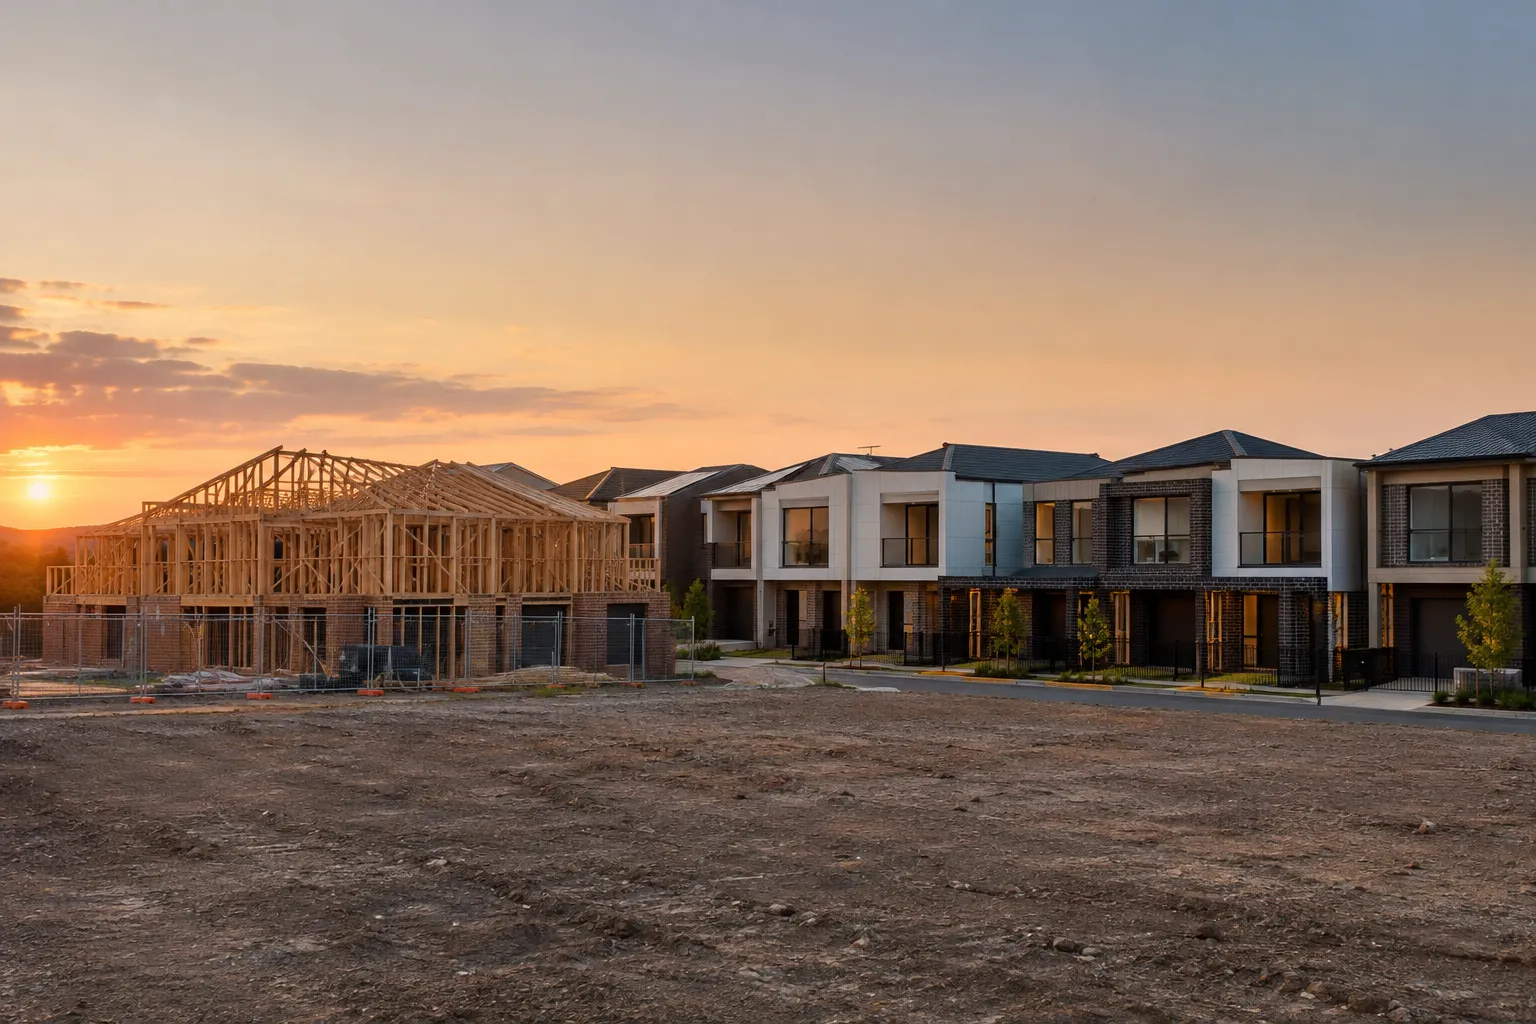
- Building on previously vacant land
- Putting more dwellings on a single lot
- Converting a non-residential building into housing
- Buying within 24 months of the first occupation certificate, from a vendor who held the property as new
Read as a policy signal, each route points capital at a different product. Vacant land and subdivision favour developers and builders with the capacity to start from scratch. Conversions favour office and commercial stock owners looking for a second life. The 24-month window favours off-the-plan and recently completed apartments and townhouses, particularly those sold by their first owner.
What the list does not reward is just as telling. Buying an established home, however well located or renovated, does not qualify. That is the intent. But it also means the tax benefit is attached to a property’s history, not to whether it adds anything to housing supply today.
Does the label actually track new supply?
The gap between the label and the outcome is where the unintended consequences sit.
A demolish-and-rebuild replacement may fail the test, even though it delivers a brand new home. One house knocked down and one house built adds no dwellings to the count. Fair enough, on a supply reading. But the investor who funds that project may still see it as new construction, and the rule treats it as something else.
Granny flats lacking separate title may also miss out. A secondary dwelling can add real capacity to a lot, yet if it cannot be sold or titled separately, the definitional path gets murky. That nudges owners toward more expensive title and subdivision work they might not otherwise choose.
Then there is the 24-month window. A buyer in month 23 qualifies. A buyer in month 25 does not. Expect sellers and agents to price and market stock around that cliff, and expect some stock to sit unsold until the clock resets in someone’s favour, or to be discounted hard as it approaches the edge.
Where classification gaming could creep in
The legislation anticipates this. An anti-avoidance rule targets schemes designed to manufacture the benefit. That is a sensible guard, but rules like this are only as good as their enforcement, and the detail of what counts as a scheme will be tested in practice, not on paper.
The pressure points are easy to imagine in general terms:
- Marginal changes to a lot to claim an added dwelling
- Questions about whether a vendor genuinely “held the property as new”
- Disputes over the date of the first occupation certificate
- Arguments about the prior use of land to fit the vacant-land route
None of that needs fraud. It only needs incentives, and a valuable deduction is a strong incentive. Where the definition has edges, some investors and vendors will probe them.
The catch for buyers
Investors who want to rely on the new-dwelling test carry the burden of proving it. That makes due diligence a tax decision as much as a property one.
Three checks stand out:
- The occupation certificate date. The 24-month window runs from it, so confirm it in writing.
- The vendor’s history. The vendor must have held the property as new, which is a question about who owned it and how it was used.
- The prior use of the land. Vacant land has a specific meaning, so do not assume a cleared block qualifies.
The catch
The bill has not passed. The committee process could alter definitions, transition rules or the anti-avoidance wording. A purchase planned around the current text carries that risk until the law is final.
What it means for supply and for readers
The stated aim is to steer investment toward new housing. The definition does that in broad terms, but it does so through a narrow gate, and gates distort. Capital will pile into whatever clearly qualifies, which may crowd some product types and starve others that add useful capacity without fitting the legal wording.
For readers weighing a purchase, the practical step is simple. Before you commit, get your accountant or a tax adviser to test the specific property against the four routes, and keep the paperwork that proves it. For background on how the wider rules interact, our negative gearing, CGT and investor tax guide is a useful starting point, and our look at how investment tax changes leave supply risk unresolved covers the supply side in more depth.
Want the weekly signal on policy changes like this? Subscribe to the newsletter.
General info, not financial advice.