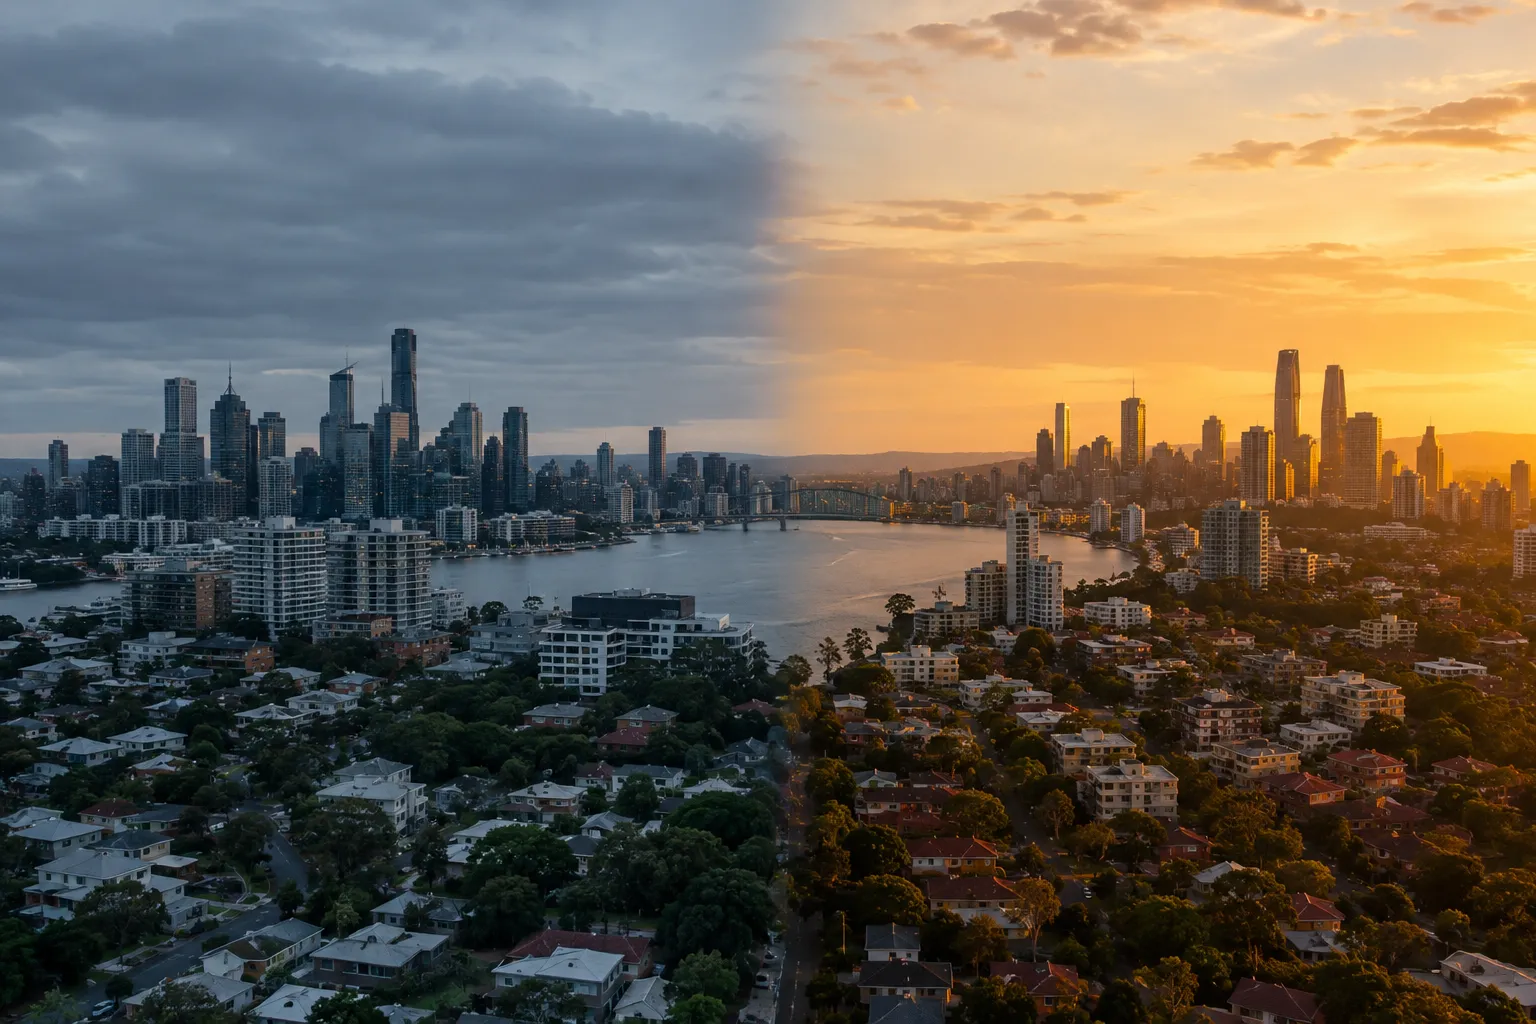
For months, the story was simple: rates up, prices soft, everyone waits. The Budget has broken that script. Australia’s post-Budget property market is no longer one market. Some cities are sliding, and others are quietly turning the corner.
We have not seen the full underlying report behind this story, only its headline claim. So treat what follows as an explanation of why a split like this is plausible, not a tally of suburb-level price moves.
Why one Budget can move cities in opposite directions
A national policy lands on very different local markets. The same change in investor tax settings hits harder where investors make up a bigger share of buyers. The same squeeze on borrowing capacity bites harder where prices are already stretched against incomes. And the same shift in sentiment matters less where there are simply not enough homes.
Three levers do most of the work:
- Who is buying (investors versus owner-occupiers)
- How much they can borrow relative to local prices
- How quickly new supply can respond
Investor tax settings: the exposure is uneven
Investors are not spread evenly across the country. Where they make up a large slice of purchases, any change that lowers after-tax returns removes a chunk of demand quickly. Some investors pause. Others sell. Both push in the same direction for prices.
Where owner-occupiers dominate, the effect is mostly indirect. Buyers there care more about their own repayments and job security than a landlord’s tax position.
In plain English: a tax change is a demand shock for the cities where investors drive activity, and a footnote for the cities where they do not.
Borrowing capacity sets the ceiling
Prices ultimately sit under what banks will lend. When serviceability tightens, the maximum loan falls, and the markets with the highest price-to-income ratios feel it first. A buyer who could stretch to a given price last year now cannot, regardless of how they feel about the market.
That is why two cities with the same rate environment can behave differently. The one where buyers were already borrowing near the limit has little room left to absorb a shock. The one where households had more headroom can wear it.
It also explains why cheaper markets are not automatically the safe ones. Lower prices help only if incomes, jobs and credit conditions hold up too. Our look at why Perth’s cheaper prices still don’t fix affordability shows how repayments, not sticker prices, decide who can actually buy.
Supply constraints: the floor under the turning cities
The cities that look like they are turning share a quiet feature: not much is being built relative to demand. When fewer homes come to market, a dip in buyer numbers can be met by sellers who simply decide to wait, and prices stop falling.
Building is not easy to ramp up anywhere. Costs are high and the pipeline is thinning, as we covered in the latest building starts data. Apartments are especially hard, because construction costs push developers toward luxury product rather than the mid-priced stock most buyers need.
Where supply is tight, weak demand is cushioned. Where there is more stock, or more room to build, the same weak demand shows up straight in prices.
What this split does and does not tell you
It does suggest that a single national headline number is now close to useless. A median across all capitals hides one group of cities falling and another group stabilising.
It does not tell you that the turning cities are about to boom. A floor is not a recovery. Rates, credit rules and household confidence can still shift, and a market that has stopped falling can stay flat for a long time.
Risks and unknowns
- Policy follow-through: Budget measures can be changed, softened or delayed, and lenders may adjust how they apply them.
- Rate path: another move in rates would hit the stretched markets again and could undo the stabilisation elsewhere.
- Investor behaviour: if landlords sell faster than expected, rental supply tightens, which can feed rents even as values fall.
- Data lag: monthly price indices trail what is happening at auction and in contracts, so early turns can be revised.
The practical step
Stop reading the national headline and look at your own market on three measures: the investor share of local purchases, the price-to-income ratio, and how much new supply is actually coming. Those three tell you more about which side of the split you are on than any single month of price data.
If you want the weekly signal on where the market is heading, subscribe to the Australian Property Review newsletter.
General info, not financial advice.