The SMSF residential property ban is live. Since 10 August 2026, Self-Managed Super Funds have been unable to use Limited Recourse Borrowing Arrangements to acquire residential property. The change, passed through the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, removes one of the most popular leveraged investment routes for Australian trustees. For anyone running an SMSF with property ambitions, the question is now what works instead.
The ban targets a specific structure: LRBAs for residential property. Business real property LRBAs remain fully permitted. Existing residential arrangements are grandfathered and can be refinanced. But no new residential borrowing is allowed. That leaves trustees with a choice: adapt the strategy or abandon leveraged property inside super.
How the ban works and what it blocks
A Limited Recourse Borrowing Arrangement lets an SMSF borrow to buy a single asset, typically property, held in a separate bare trust. If the fund defaults, the lender’s claim is limited to that asset. The rest of the fund is protected.
The new law amends subsection 67A(2) of the Superannuation Industry (Supervision) Act 1993. Starting 10 August 2026, an LRBA can only fund a purchase that meets the business real property test, and residential property fails that test outright.
What this blocks: residential houses, apartments, serviced apartments, Airbnb properties, mixed-use buildings with a residential component.
What it does not block: commercial premises, factories, warehouses, offices used wholly and exclusively in a business.
The test is strict. A property zoned commercial but sitting vacant may still fail. A retail shop with a residential flat above it will fail. The ATO applies the business real property definition exactly as written in section 66(5) of the SIS Act: the property must be used wholly and exclusively in one or more businesses.
Business property LRBAs are still on the table
For business owners, nothing fundamental has changed. Buying your own commercial premises through your SMSF via an LRBA remains a viable, tax-effective strategy.
The fund borrows to acquire the property. The business pays rent to the SMSF. Rental income is taxed at 15 per cent in accumulation phase, zero in pension phase. The asset sits inside the fund, protected from business creditors. Long-term capital growth accrues to the super balance.
The property must be used wholly and exclusively for business purposes. A warehouse used by your logistics company qualifies. An office building leased to your accounting practice qualifies. A retail premises with a residential unit upstairs does not.
Trustees and brokers should confirm the business real property classification before proceeding with any LRBA application. A failed classification can be treated as a breach of the SIS Act, with penalties and potential fund disqualification.
Existing arrangements are protected
If you already have a residential LRBA in place, it can continue to its natural conclusion. The legislation fully grandfathers existing arrangements. No requirement to unwind, restructure or repay early.
Refinancing is also explicitly permitted. Trustees can switch lenders, renegotiate interest rates or extend loan terms on an existing residential LRBA without triggering the ban.
The refinance must be genuine. A material alteration to the structure, such as changing the bare trust, adding a new borrower or significantly altering loan terms, could be treated by the ATO as a new arrangement. Professional advice is recommended before proceeding.
Timing matters too. An SMSF that had already exchanged contracts on a residential purchase before 10 August 2026 keeps that deal grandfathered, even if settlement does not close until after the ban starts. Trustees in this position should keep clear documentation of the contract exchange date.
Alternatives for trustees who relied on residential LRBAs
Trustees who previously used residential LRBAs to build property exposure now need a different approach. The options depend on the fund’s liquidity, investment objectives and willingness to accept complexity.
Unencumbered residential purchases: The SMSF buys the property outright using cash reserves. No borrowing, no LRBA, no restrictions. That means having enough cash on hand to cover the purchase price outright, plus stamp duty and settlement costs. For funds with substantial balances, this remains the simplest path.
Business real property LRBAs: For business owners, this is the most direct leveraged property route still available. Buy your own commercial premises through the SMSF, pay rent to the fund, benefit from tax-effective income and long-term capital growth.
Fixed unit trusts: The SMSF holds units in a fixed unit trust that owns property. The remaining units in the trust are typically held by other members or outside investors, who arrange their own finance independently. The SMSF participates in property investment without borrowing. This structure requires careful legal setup.
Superannuation Unrelated Investment Trusts (SUITs): Pool capital with genuinely unrelated parties in a trust permitted to borrow for larger or higher-quality assets. No one party is allowed to control the trust outright, and structuring one properly takes specialist legal and financial input.
Listed property trusts (REITs): Invest in Australian Real Estate Investment Trusts for property exposure with liquidity, diversification and no borrowing at the fund level. REITs are simpler than direct ownership and carry lower concentration risk.
Gearing outside superannuation: Buy the residential property outside super altogether, held in a personal name, family trust or company structure instead. This sacrifices the tax advantages of the super environment but offers greater flexibility on leverage, asset type and access to funds.
Risks to watch
The business real property test is strict and the ATO applies it exactly. A property that looks commercial but is partly vacant or has a minor residential component can fail the test, triggering a breach. Trustees using fixed unit trusts or SUITs must ensure the structure genuinely involves unrelated parties, or the ATO may treat it as a prohibited related-party transaction. Refinancing an existing residential LRBA is permitted, but a material alteration to the arrangement could be treated as a new borrowing and disallowed.
The ban reflects a long-standing ATO concern about concentration risk, liquidity risk and the potential for SMSF borrowing to be used for purposes inconsistent with the sole purpose test. The policy position has been debated since the Cooper Review in 2010. The 2026 ban closes the door on new residential LRBAs, but it does not close the door on SMSF property investment.
What it does is force trustees to choose: accept higher upfront liquidity requirements for residential property, shift focus to commercial property where the business real property test is met, or explore alternative structures that allow property exposure without direct SMSF borrowing.
How this intersects with broader property tax changes
The SMSF residential property ban is part of a wider shift in how Australian property investment is taxed and regulated. Recent property tax changes have already forced investors to reassess negative gearing, capital gains treatment and depreciation schedules. The SMSF ban adds another constraint to the playbook.
For trustees who hold residential property outside super, the question is whether to continue gearing personally or shift capital into the SMSF for unencumbered purchases. For business owners, the commercial property LRBA route remains the most tax-effective leveraged option. For everyone else, the trade-off is liquidity versus leverage.
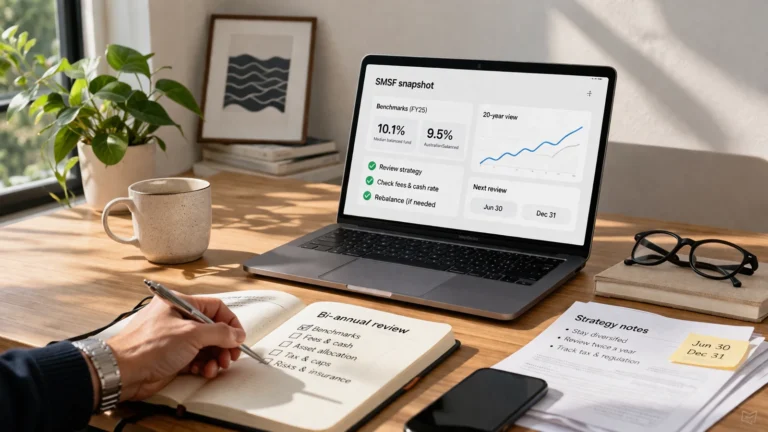
Start here: if your SMSF strategy relied on residential LRBAs, audit your alternatives now. Business owners should consider commercial property LRBAs. Trustees with sufficient liquidity should model unencumbered residential purchases. Those seeking diversification should evaluate REITs or fixed unit trusts. Subscribe to Australian Property Review for weekly analysis on SMSF strategy, property tax and market structure changes.
General info, not financial advice.