Traditional home ownership, detached house, couple or family, single title, is losing ground to models that split the difference between renting and solo ownership. Co-housing, where groups of households own separate dwellings within a shared development, is one of the fastest-growing alternative structures, and the reasons driving uptake have shifted from lifestyle preference to hard economics.
The shift matters because it signals a structural change in how a slice of the market will build equity and plan retirement. The problem: Australia’s finance, tax and estate planning frameworks still treat co-housing as a niche edge case, creating both opportunity for early movers and traps for those who don’t stress-test the fine print.
What co-housing actually is
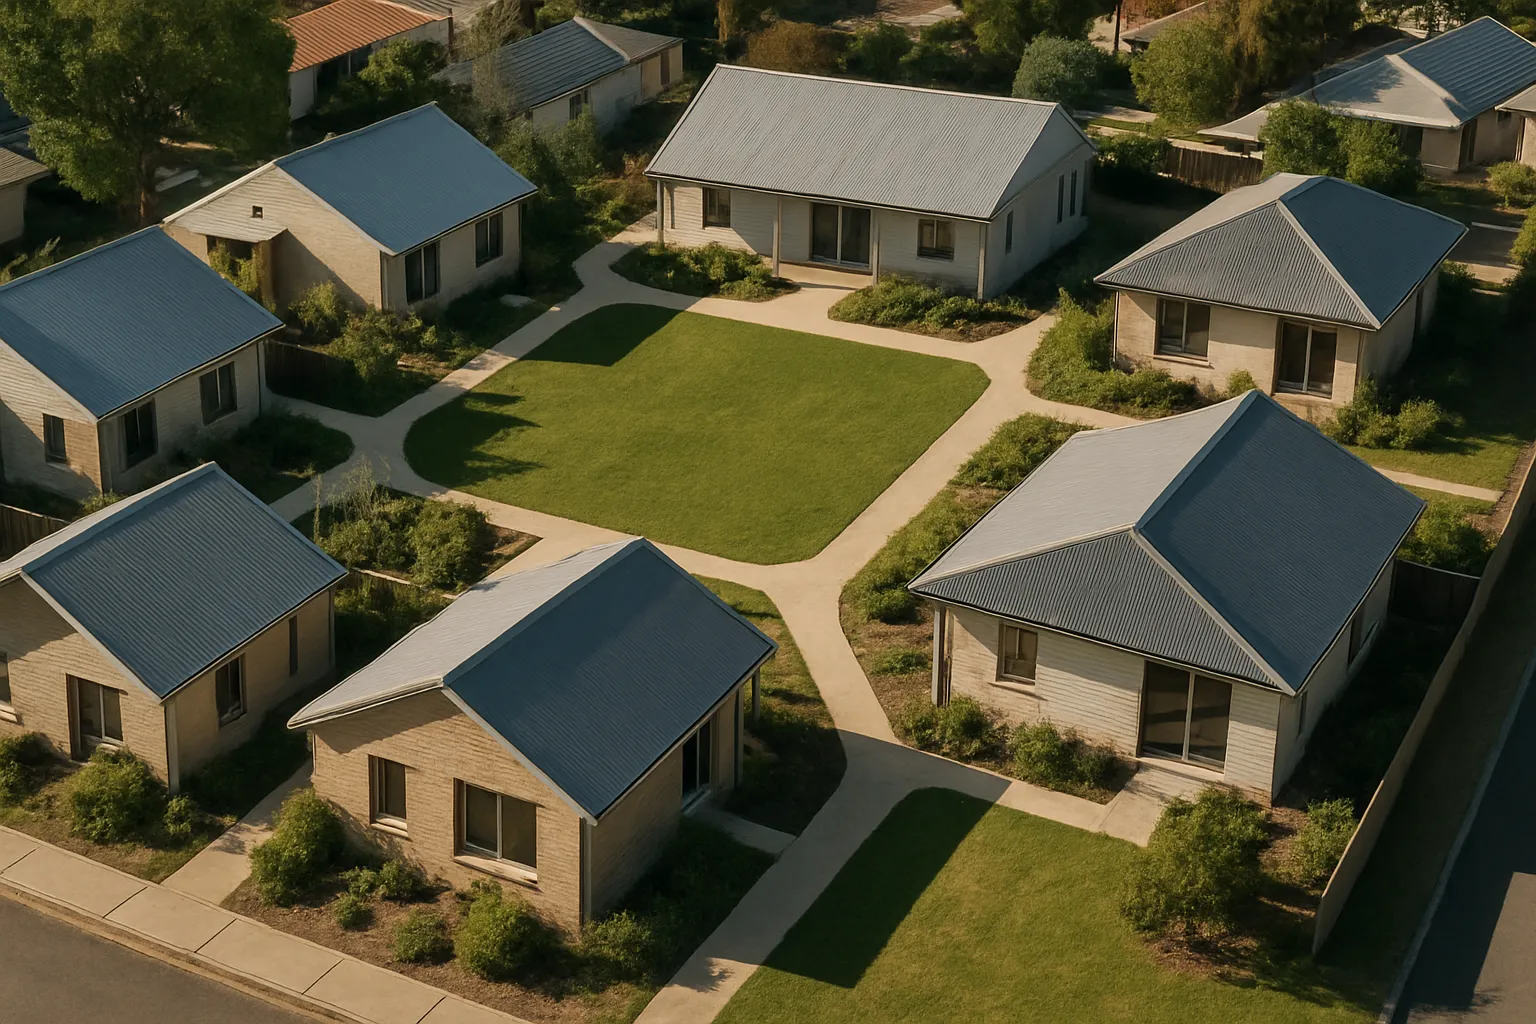
Co-housing groups own individual titles to their dwelling (house or apartment) plus shared ownership of common facilities, garden, workshop, dining hall, guest rooms. Governance is collective, design is intentional (smaller private spaces, larger shared areas), and the model reduces per-household land and infrastructure costs.
It’s not a commune, not a strata scheme in the usual sense, and not a retirement village with an operator extracting fees. Ownership is freehold or long-term leasehold, resale rights sit with the household, and decision-making runs through a co-op or body corporate structure depending on the legal vehicle.
The model has existed in Denmark and the Netherlands since the 1970s, in pockets of Australia since the 1990s, but uptake was slow while housing was affordable enough for the old playbook to work.
Why it’s gaining traction now
Three pressures are pushing co-housing from fringe to mainstream consideration:
- Deposit barriers: median house prices in Sydney and Melbourne sit above $1 million, locking out single buyers and forcing pooling strategies. Co-housing lets two or three households split land costs without sharing a dwelling.
- Ageing renters: the number of Australians over 55 renting privately has doubled in a decade. With super balances below the threshold needed to buy solo, shared equity models become the only path to ownership before retirement.
- Pension treatment uncertainty: owning a full house doesn’t guarantee a full pension exemption if you’re sharing equity structures, but renting until 70 guarantees nothing. Co-housing sits in the middle, and some retirees are rolling the dice.
The appeal used to be lifestyle (community, sustainability, shared resources). That still matters, but the dominant driver now is affordability, households who can’t afford solo ownership but want equity exposure and control over their housing future.
The catch
- Financing: most lenders treat co-housing as non-standard security. Expect higher deposits (25–30%), limited product choice, and slower approval times. Construction finance is harder again, banks price the risk that the group won’t complete or that resale will be illiquid.
- Legal structure risk: if the co-housing entity is structured as a company title or co-op, you don’t own real property, you own shares that entitle you to occupy. That can trigger capital gains tax on disposal, block access to the pension exemption, and complicate estate transfers.
- Resale liquidity: selling a co-housing share means finding a buyer the existing group will approve. In a downturn, that could mean months on market or a discount to comparable freehold stock.
- Governance complexity: you’re co-owners of common property and decision-makers on maintenance, new members, and rule changes. If the group fractures, the legal and financial disentanglement can be messy and expensive.
Where the policy and finance gaps sit
Australia has no dedicated co-housing legislation. The structures bolt together elements of strata law, co-op law, and company title rules, depending on the state and the legal advice the group received. This creates inconsistency:
- Stamp duty: some states charge duty on the full development value upfront, others on individual dwelling transfers. The difference can be tens of thousands per household.
- Pension asset test: Centrelink treats freehold co-housing dwellings as exempt (like any principal home), but company title or co-op shares may be assessed as financial assets, reducing the age pension.
- Tax treatment: if the co-housing entity rents out common facilities or guest rooms to offset costs, is that assessable income for all members? The ATO has issued private rulings but no public guidance.
Banks haven’t built standard credit policies either. Each application is a one-off negotiation, which adds time, cost, and the risk that finance falls through mid-development.
Scenarios over the next five years
Base case: co-housing remains a small but growing slice (under 2% of new housing stock), driven by retirees pooling super, single buyers splitting deposits, and intentional community groups. Financing stays non-standard, resale stays niche, but a handful of state governments start piloting land release or planning incentives.
Upside: a federal or state government introduces co-housing-specific legislation (legal structure, financing pathway, tax clarity), a major bank launches a dedicated co-housing loan product, and uptake accelerates as the model becomes legible to mainstream buyers.
Downside: a high-profile co-housing dispute (group fractures, members can’t sell, costly legal battle) gets media coverage, banks tighten credit further, and the model stays marginal. Alternatively, a recession hits resale liquidity hard, and early adopters discover their co-housing share is worth 20–30% less than comparable freehold stock.
What this means if you’re considering co-housing
Stress-test three things before committing:
- Finance: get unconditional written approval before signing anything. Assume 30% deposit, compare at least three lenders, and factor in higher interest rates (0.5–1% above standard variable).
- Legal structure: insist on freehold title to your dwelling if pension exemption or estate simplicity matters. Avoid company title or co-op structures unless you’ve modelled the tax and Centrelink impact with a specialist.
- Exit plan: assume resale will take 6–12 months longer than comparable freehold stock. If you need liquidity (health crisis, job relocation), you may be forced to discount or wait.
If you can’t tick all three, co-housing is higher risk than it looks. If you can, it’s a legitimate strategy for entering ownership when solo buying is out of reach, but only if you’re comfortable with governance complexity and a smaller resale market.
Bottom line
Co-housing is shifting from lifestyle experiment to affordability response, which means more Australians will consider it over the next decade. The problem: the legal, tax and finance infrastructure treats it as a fringe case, so early adopters carry execution risk that traditional buyers don’t face.
If housing affordability keeps deteriorating and government doesn’t deliver supply at scale, expect co-housing to grow regardless of policy support, the question is whether banks and regulators catch up in time to make it less risky, or whether early movers pay a premium for pioneering a model the system isn’t ready for.
For more on how shared ownership affects wealth and estate planning, see Living apart together property strategy: when separate homes protect wealth.
Want the signal on policy shifts and financing changes? Subscribe to the newsletter.
General info, not financial advice.