When a publicly traded property trust trades below its net tangible assets for months, two narratives compete. Either the market has mispriced quality assets and patient capital wins, or the book value itself overstates what those assets would fetch if sold today. A hostile bid targeting a lifestyle communities operator this month forces that question into the open.
The tension matters because REIT valuations set the benchmark for private property deals, mortgage serviceability assumptions, and whether institutional money flows into Australian residential assets or elsewhere. When a raider bids for control at a discount to book value, it’s either opportunistic or a market signal that the accounting doesn’t match reality.
Why book value splits from market price
REITs calculate net tangible assets by marking property portfolios to fair value, typically using independent valuations updated every six to twelve months. Those valuations rely on capitalisation rates applied to rental income, plus assumptions about future demand, development potential, and exit pricing.
Market price reflects what investors will pay today for a share in those assets, adjusted for leverage, management quality, liquidity, and forward earnings risk. When the gap widens, one of three things is happening: valuations lag a market shift, the market is wrong, or there’s a structural discount baked into the vehicle itself.
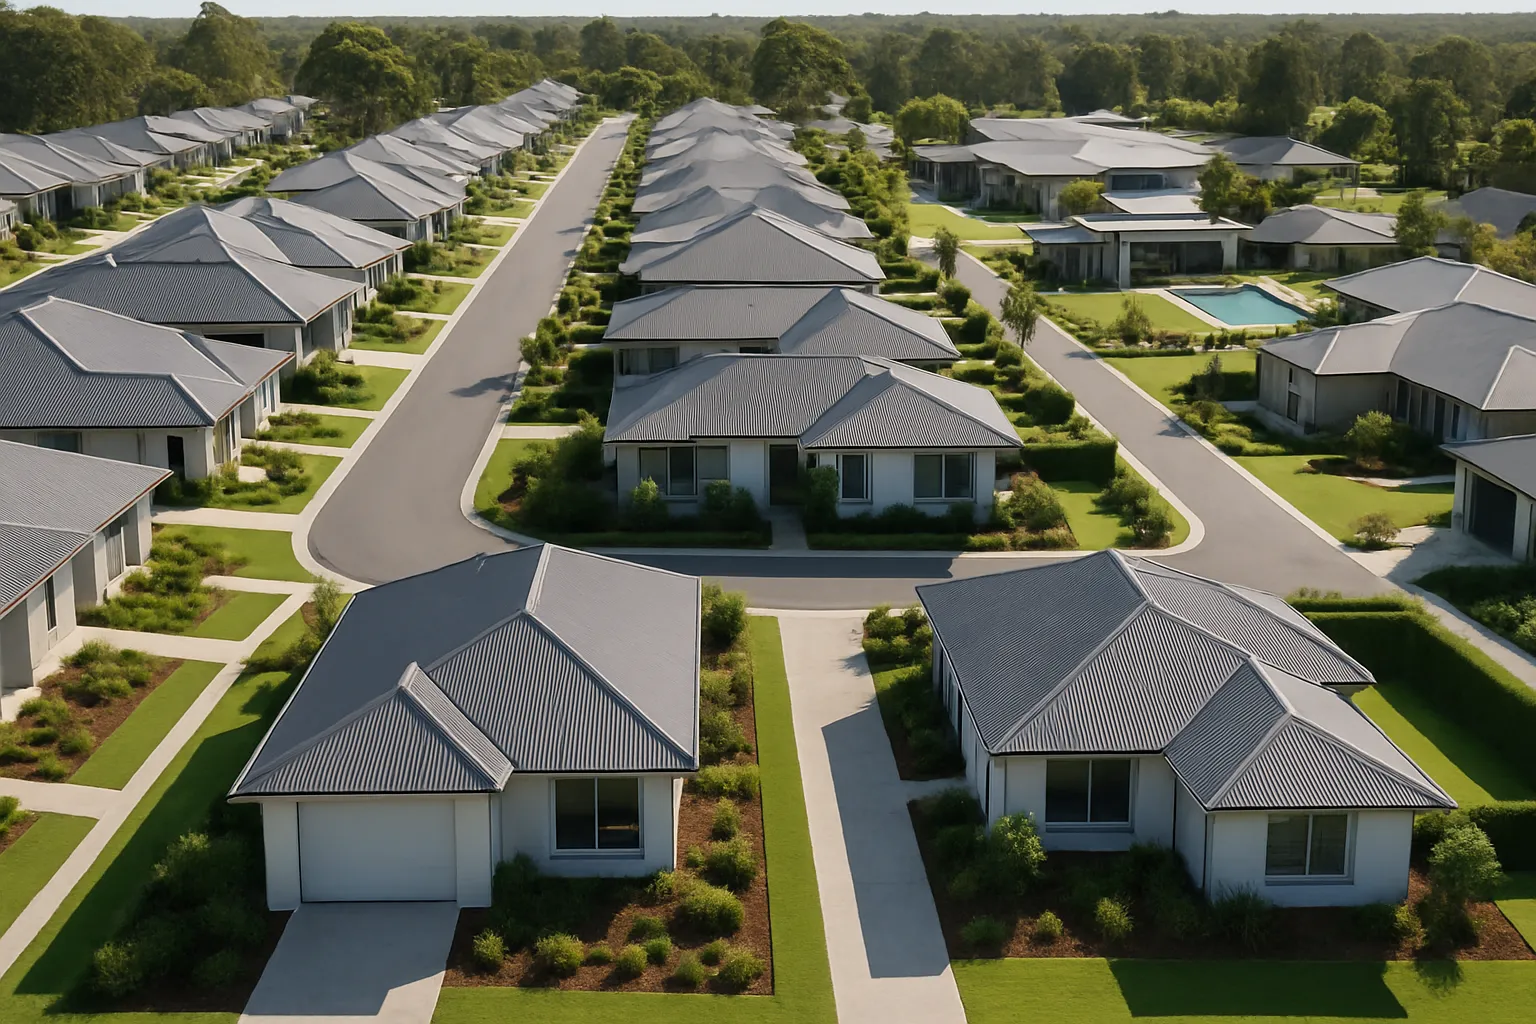
Lifestyle communities and land lease parks carry additional complexity because the revenue model mixes site fees, deferred management fees, and capital gains on home resales. Valuing that mix requires assumptions about turnover rates, buyer demand among retirees, and how aggressively a competitor might harvest near-term cashflow versus long-term capital.
The bidder’s thesis versus the sceptic’s view
A hostile offer at a premium to current share price but below book value suggests the acquirer believes one of two things: either the assets are mispriced by the market and can be managed better under private ownership, or the reported book value overstates what those assets are worth but the bid still makes sense at the lower true value.
If the first case holds, patient unitholders who rejected the bid and rode out volatility would eventually see value crystallise as the market re-rates or assets are sold individually. If the second case holds, the bid is actually close to fair value and those who hold out risk further markdowns when the next valuation cycle reflects weaker transaction evidence.
The sceptic’s counter-argument points to higher interest rates, stretched affordability even in the downsizer segment, and a pipeline of new supply that pressures both occupancy and pricing power. If cap rates widen another 50 basis points across the sector, book values fall and the hostile bid starts to look like full price, not opportunistic.
The catch
- Hostile bids cluster when share prices trade 15–25% below book value for more than six months
- Independent valuations update slowly and may not capture a rapid shift in buyer appetite or debt costs
- A successful takeover at a discount to book resets the valuation benchmark for the entire sector
- Shareholders face a choice with incomplete information: accept a certain premium now or bet that book value holds
What recent transaction evidence shows
Private sales of comparable assets over the past twelve months offer the cleanest test of whether book values are realistic. In the manufactured housing and lifestyle community segments, transaction volumes have thinned, but the deals that have closed suggest buyers are pricing in slower income growth and higher exit cap rates than valuations assumed eighteen months ago.
One bellwether deal saw a major operator acquire a significant land bank aimed at the downsizer wave, paying for development-stage lots rather than stabilised communities. That transaction priced future supply, not current income, and the implied return hurdles were materially higher than prevailing REIT valuations for operating assets at the time.
If private buyers are demanding higher returns for lower-risk operating assets than they were two years ago, book values based on older cap rates and growth assumptions will overstate current pricing. The gap isn’t permanent, but it takes time for valuations to catch up, and in the interim, hostile bids exploit the disconnect.
The trade-offs for different investors
Institutional holders with long time horizons and low cost of capital can afford to ignore short-term share price volatility if they believe the underlying assets will deliver target returns over a decade. They’re effectively marking to model, not to market, and a hostile bid below book value doesn’t change their thesis unless it succeeds and forces a sale.
Retail investors and superannuation members don’t have that luxury. A 20% discount to book value that persists for two years is a real loss if you need liquidity, even if the assets themselves haven’t deteriorated. The hostile bid offers a floor and a choice: take the premium now or wait for value to emerge, with no certainty on timing.
Traders and opportunistic funds view the gap as a spread to arbitrage. If the bid succeeds, they clip the premium. If it fails and management responds with asset sales or a buyback, the share price re-rates. Either outcome works as long as the position is sized correctly and the holding period is flexible.
Scenarios over the next nine months
Base case: the hostile bid is rejected, management announces a strategic review including asset sales or a portfolio restructure, and the share price trades up 10–15% as the market prices in value realisation. Book value remains stable but the discount narrows as uncertainty reduces.
Upside: a competing bid emerges at a higher price, or the original bidder raises its offer after due diligence confirms asset quality. Shareholders who held out capture the full premium, and the sector re-rates as the transaction sets a new benchmark.
Downside: the bid lapses, no competing offer materialises, and the next round of independent valuations marks assets down 8–12% to reflect weaker transaction evidence and higher cap rates. The share price falls further below the new lower book value, and the discount widens rather than closes.
Pressure points to watch
Interest rate settings over the next two quarters will determine whether buyers in the downsizer and retiree segments can access mortgage finance at serviceable rates. A sustained pause supports demand and stabilises occupancy; further hikes reduce the pool of cashed-up upgraders and slow turnover in existing communities.
New supply coming online in key markets will test pricing power. If competing developments undercut site fees or offer better amenities, established operators face a choice between defending occupancy with discounts or accepting higher vacancy. Either path pressures income and valuations.
Debt refinancing for the sector is a mechanical risk. Many REITs termed out facilities in 2021–2022 at sub-4% rates; rolling those over at current margins compresses distributable income and may force asset sales to reduce leverage. If forced sales happen into a weak bid environment, transaction evidence deteriorates further and book values follow.
If you’re weighing a REIT position now
Start with the discount to book value and ask whether it’s justified by sector headwinds or a temporary mispricing. If the trust has quality assets, conservative leverage, and management with a track record of navigating cycles, a 20% discount may be an entry point. If the assets are levered, face near-term refinancing, or operate in oversupplied markets, the discount might be telling you book value is overstated.
Check recent transaction evidence for comparable assets and compare the implied cap rates to what the REIT’s valuations assume. A 50-basis-point gap suggests meaningful downside risk to book value. No recent transactions at all is a red flag: it means buyers aren’t willing to test the valuation thesis at any price close to book.
Size the position assuming book value could fall 10–15% before it stabilises, and only commit capital you can hold through that scenario without forcing a sale. Hostile bids create volatility and forced decisions; the investors who profit are the ones who can afford to wait for value to crystallise on their timeline, not the bidder’s.
Subscribe to the newsletter for weekly analysis on property market signals and what’s moving institutional money in and out of Australian residential assets.
General info, not financial advice.