Most Australians never change their super investment option after their employer sets it up. That inertia compounds into a retirement shortfall that can reach $230,000 for younger workers, a figure driven by the conservative asset mix most default options use and the decades those lower returns have to multiply.
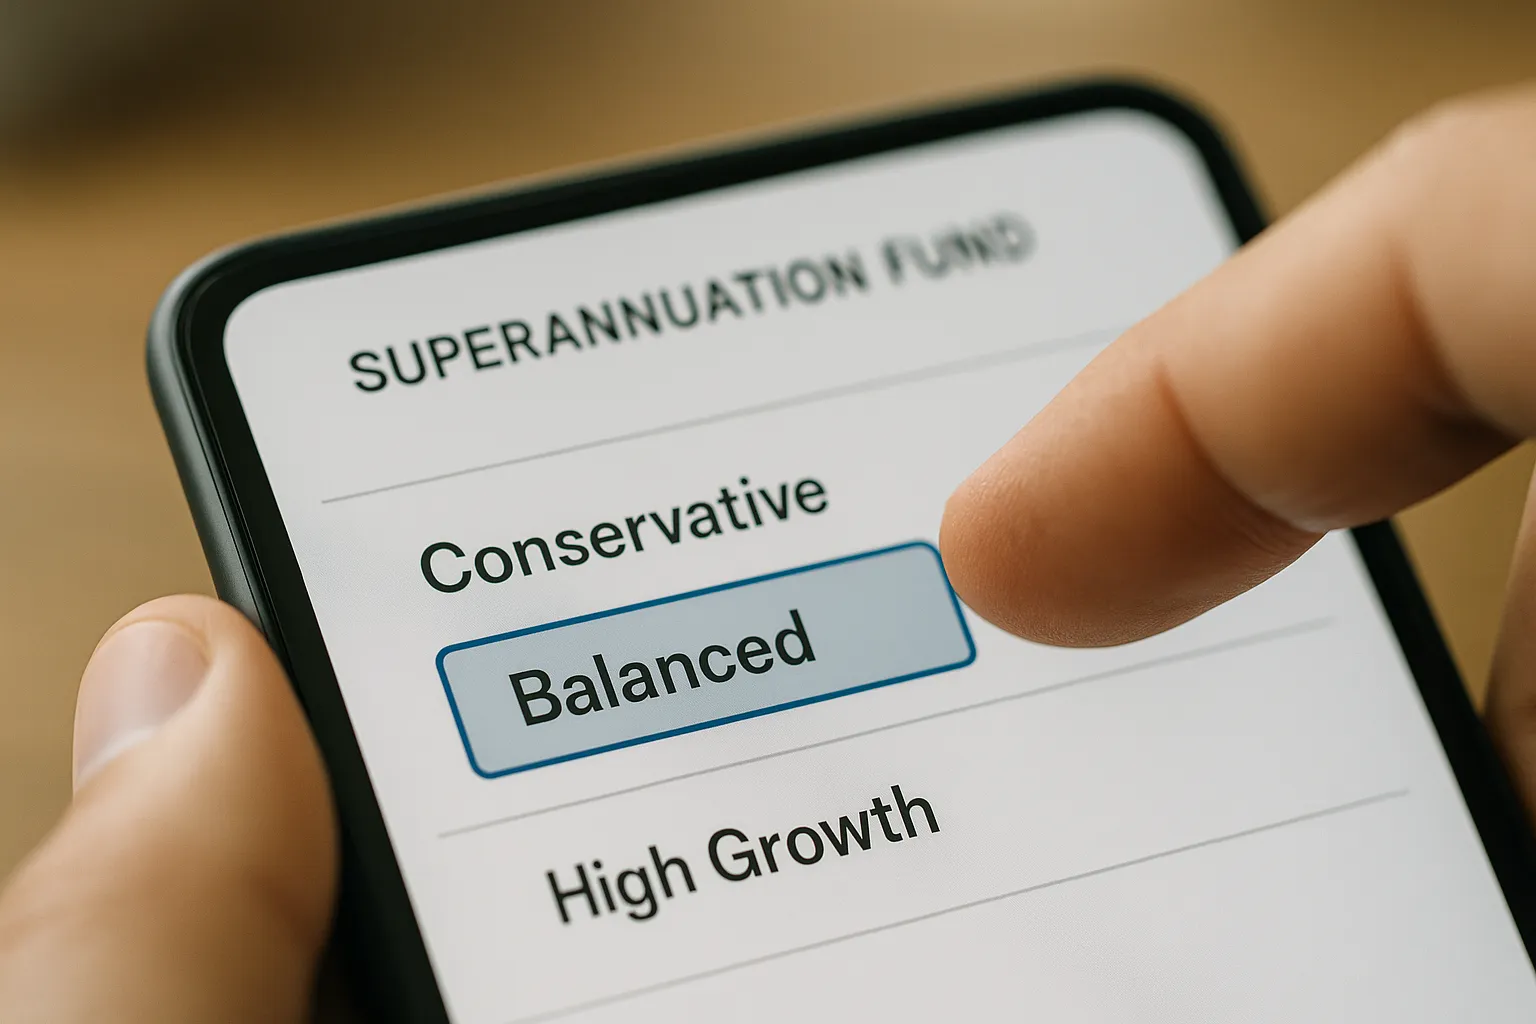
The default option in most super funds is a balanced or MySuper product: roughly 70% growth assets (shares, property) and 30% defensive (bonds, cash). It’s designed to suit the widest possible member base, which means it’s not optimised for anyone in particular. For a 25-year-old with 40 years until retirement, that 30% defensive allocation is dead weight, protection against short-term volatility they don’t need and growth they can’t afford to miss.
How the $230k gap builds
The difference comes down to return assumptions and time. A balanced fund might return 6.5% per annum over the long term, while a high-growth option (85-95% growth assets) could deliver 7.5-8%. On a starting balance of $50,000 with $10,000 annual contributions, that 1-1.5 percentage point gap turns into $180,000-$230,000 less at age 65, depending on fee structures and actual market performance.
The compounding effect accelerates over time. In the first decade, the difference might only be $15,000-$20,000. By year 30, it’s $100,000. The final ten years add another $80,000-$130,000 as the larger balance in the growth option generates higher absolute returns even if the percentage gain stays constant.
This assumes both options are left untouched for 40 years, which is rare in practice, but even workers who switch at age 35 or 40 leave significant money on the table during the years they stayed in the default.
Key numbers
- Balanced option typical allocation: 70% growth, 30% defensive
- High-growth option typical allocation: 85-95% growth, 5-15% defensive
- Long-term return difference: 1-1.5 percentage points per annum
- Retirement balance gap after 40 years: $180k-$230k on a $50k starting balance with $10k annual contributions
- Percentage of members who actively choose their investment option: approximately 15-20%
Why so few people switch
Inertia is the primary factor. Super feels distant, the terminology is opaque, and the default option is presented as safe and suitable. Many workers assume their employer or fund has chosen the best option for them, or they simply never revisit the decision after the initial signup.
The second barrier is fear of volatility. High-growth options fluctuate more in the short term, and seeing a balance drop 10-15% in a bad year feels like a loss even if the long-term trajectory is higher. Balanced options smooth out those swings, which provides psychological comfort but comes at a measurable cost for members with long time horizons.
The third issue is information asymmetry. Funds are required to show past performance and risk labels (high, medium, low), but they rarely quantify the retirement dollar impact of staying in the default versus switching. A projected balance comparison at age 65 would make the trade-off explicit, but most member dashboards don’t surface that calculation.
Who this hits hardest
Younger workers lose the most in absolute dollars because they have the longest compounding window. A 25-year-old in a balanced option for their entire career could retire with $230,000 less than an identical worker who switched to high growth at the start.
Workers with interrupted careers, parents taking time off, contractors with gaps between roles, lose compounding years they can’t get back. For them, maximising returns during working years is even more critical because they have fewer contribution years to make up ground.
Higher earners feel the impact in percentage terms less than in raw dollars, since their larger balances amplify the return difference. A $500,000 balance at age 50 growing at 6.5% versus 7.5% for 15 years is a $150,000+ gap on its own.
The alternative and how to action it
For members under 50 with stable employment and no plans to access super early, a high-growth option is the baseline. That means 85-95% in shares and property, 5-15% in defensive assets. Some funds offer a 100% growth option; others cap it at 90%. Either works, the key is minimising the defensive allocation you don’t need yet.
The switch process takes 10 minutes: log into your fund’s member portal, navigate to investment options, select high growth (or the equivalent label, some funds call it aggressive, growth, or equities-focused), confirm the change. Some funds allow partial switches if you want to test the water, but splitting between options dilutes the benefit.
Risk check: if you’re within 10 years of retirement, planning to buy property soon and need to access super early under a scheme like the First Home Super Saver, or you’re in an industry with high redundancy risk and might need to lean on super as a safety net, a balanced option has a case. Outside those scenarios, the long-term cost of staying defensive outweighs the short-term volatility protection.
What could derail the strategy
A sustained flat or negative equity market over 10-15 years would erode the growth option advantage, though historically that’s rare, even the 2000s “lost decade” for US shares saw positive returns in Australian equities and global diversified portfolios. The bigger risk is behavioural: switching to growth then panicking and selling to cash during a downturn locks in losses and misses the recovery.
Regulatory changes could also shift the equation. If the government introduces stricter default option rules or mandates lifecycle investment paths (automatically de-risking as members age), the gap between default and active choice might narrow. Right now, though, that’s not on the table.
Fees matter too. A high-growth option with 0.9% fees versus a balanced option with 0.6% fees could offset some of the return advantage, depending on fund size and structure. Check the fee schedule before switching, if the growth option costs more than 0.2-0.3 percentage points extra annually, the net benefit shrinks.
Bottom line: make the decision once
The $230,000 figure assumes 40 years of compounding, but even switching at age 35 or 40 closes $80,000-$120,000 of the gap. The decision doesn’t require ongoing management, once you’re in a high-growth option, leave it alone and let time do the work. The only adjustment needed is a gradual shift toward balanced or conservative options 5-10 years before retirement, which you can set as a future reminder rather than an immediate action.
If you’re under 50, have a stable income, and haven’t reviewed your super investment choice in the last two years, check how mortgage versus super contributions trade off here, then log into your fund and compare your current option against the growth alternative. The gap is measurable, the fix is simple, and the window to benefit from it closes a little more each year you wait.
For weekly breakdowns on super, rates, and property decisions that compound over time, subscribe to Australian Property Review’s newsletter.
General info, not financial advice.