The numbers tell a story about where some Australian property investors are now looking when they run the numbers on their next purchase. Year-on-year search activity from Australia for New Zealand residential listings climbed 189.8 per cent in August, according to data from a trans-Tasman property portal. That’s not a typo, searches nearly tripled.
The timing matters. In April, the increase sat at 62.9 per cent. By May, after the federal budget landed with changes to negative gearing and capital gains tax settings, it had jumped to 163.4 per cent. By August, it had pushed past the 189 per cent mark. Saved properties, inquiries and session depth all moved in the same direction.
The question isn’t whether the search activity is real, it clearly is. The question is what it signals about how investors are pressure-testing their options, and whether this represents an actual reallocation of capital or just a lot of comparative browsing.
What’s pushing attention offshore
Three factors are showing up in the data as likely drivers. First, the federal budget changed the economics of holding negatively geared Australian property for some cohorts. The announced reforms tighten deductibility and increase the effective tax on gains for properties purchased after a certain date. That shifts the maths on cashflow and exit assumptions.
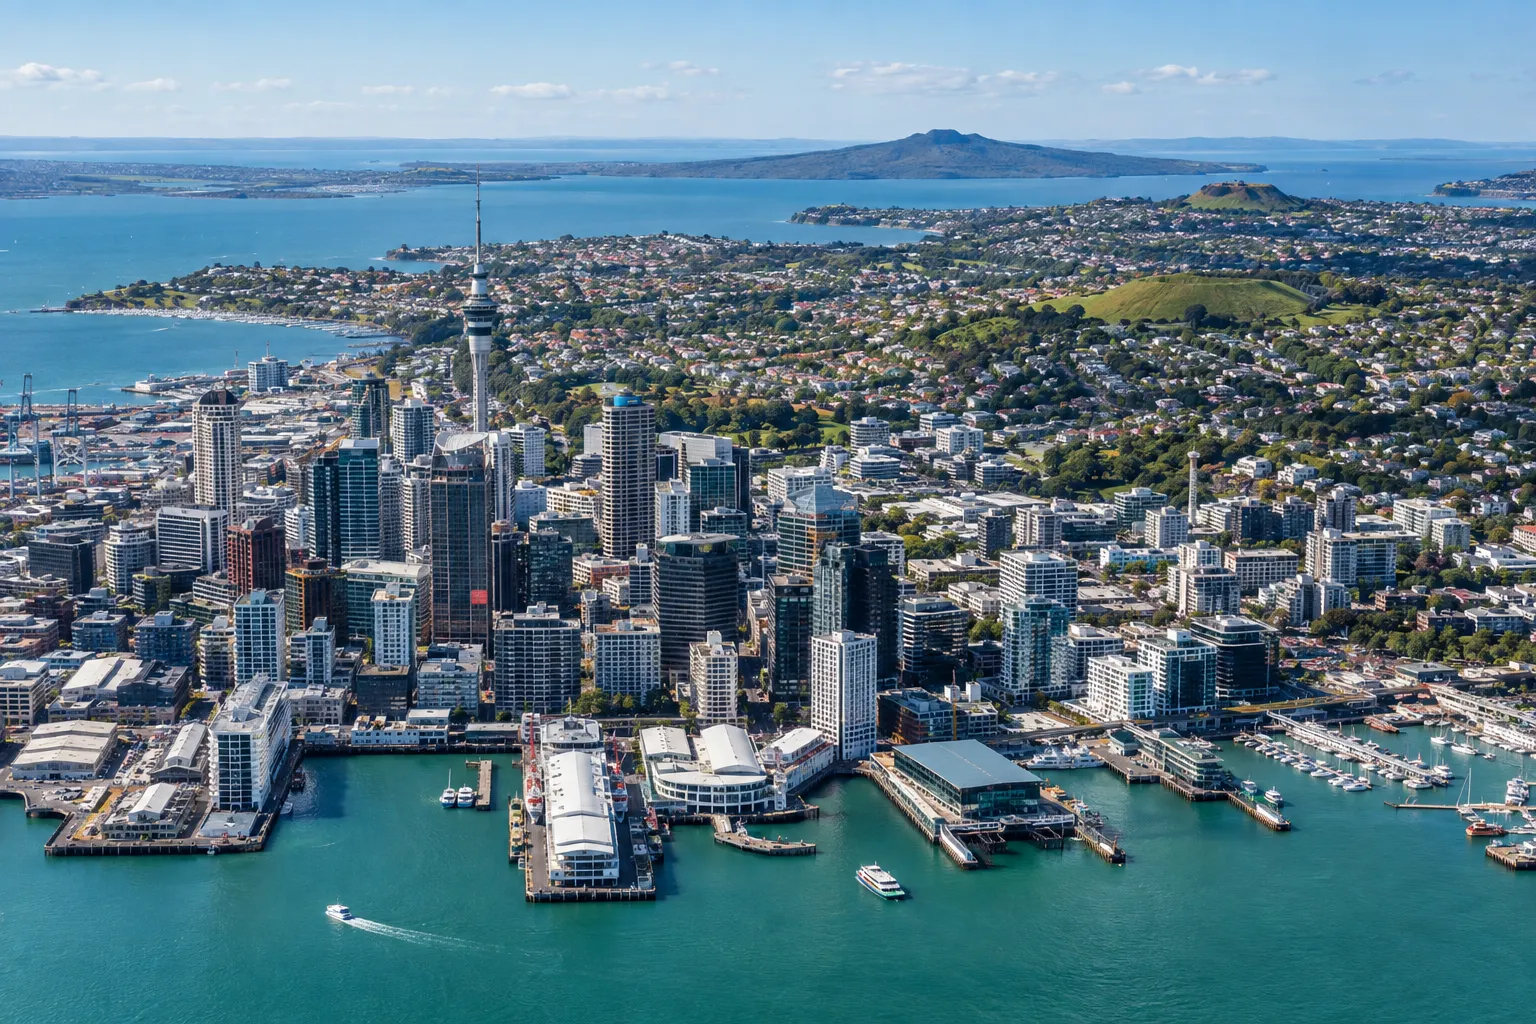
Second, New Zealand’s current settings offer a different mix of costs and opportunities. Stock levels have increased, Auckland listings were up 11.5 per cent year-on-year in August, and prices have been relatively flat. The exchange rate favours Australian buyers. For an investor running scenario models across multiple jurisdictions, the comparison now looks different than it did 18 months ago.
Third, search behaviour from Sydney, Brisbane and Perth all spiked, but engagement metrics, saves per session, inquiries per search, were higher in Brisbane and Perth than Sydney. That suggests investors in those cities, where local price growth has been sharper and yields tighter, may be doing more than just casual window-shopping.
The gap between searches and settlements
Search activity is a leading indicator of intent, not evidence of transactions. Browsing offshore listings costs nothing. Buying offshore property involves foreign investment approvals (where applicable), currency exposure, financing in a different jurisdiction, distance from the asset, and unfamiliarity with local tax, tenancy and council rules.
Most Australian investors who search New Zealand property will not buy. The friction is real. But the scale of the increase, particularly the step-change between April and May, suggests a meaningful subset are now actively evaluating options they weren’t considering a year ago.
If even a small percentage of that search volume converts into actual offshore purchases, it represents capital that would otherwise have flowed into Australian residential stock. That has two effects: it reduces competition (and upward price pressure) in the Australian markets those investors would have targeted, and it potentially slows new supply if developer feasibility models were banking on that investor cohort to absorb off-the-plan stock.
Risks if you’re considering this
Offshore property investment introduces risks that domestic purchases don’t carry. Currency moves between now and exit can erase years of rental yield. Tenant protections, council rates structures, and tax treatment of offshore-held assets differ materially across jurisdictions. Distance makes property management harder to oversee directly.
New Zealand’s regulatory settings can shift, just as Australia’s did. A future government could tighten foreign ownership rules, change depreciation schedules, or alter tax treatment of offshore landlords. You’re taking policy risk in two countries, not one.
Financing is another pressure point. Australian lenders treat offshore property differently, expect higher deposits, higher rates, and more documentation. New Zealand lenders may offer better terms, but you’re borrowing in NZD and (likely) earning in AUD, which creates a mismatch if the currency moves against you.
Risks to watch
- Currency volatility eroding AUD-equivalent returns over the hold period
- Policy changes in New Zealand restricting foreign ownership or tax settings
- Distance from asset making tenant/maintenance issues harder to resolve
- Financing costs higher than comparable Australian investment loans
- Unfamiliarity with local council, tenancy and tax obligations creating compliance risk
What this means for Australian housing supply
If offshore search activity converts into actual capital outflows, the impact shows up in two places. First, reduced investor competition in the Australian precincts and price brackets those buyers would have targeted. That’s a modest cooling force on prices in segments where investors have been active, inner-city apartments, newer townhouse estates, lifestyle regions with strong short-term rental potential.
Second, slower investor absorption affects new supply. Developers building off-the-plan stock in Brisbane, Perth and Sydney have been relying on investor presales to reach financing thresholds. If a material portion of that cohort now allocates capital to Auckland or Christchurch instead of Brisbane or Perth, some projects will stall at the presale stage. That delays supply, which eventually tightens the market again, but the timing lag is long.
The other scenario is that this is mostly browsing. Investors run the numbers, realize the all-in cost and risk profile offshore doesn’t beat the adjusted Australian opportunity, and stay local. Search volume drops back toward trend over the next six months. In that case, the cross-Tasman spike was a blip, not a shift.
The practical take
If you’re an investor pressure-testing your next move, treat offshore property as you would any other alternative allocation: model the downside case, not just the upside. Run scenarios where the NZD weakens 10 per cent, where vacancy sits at twice your base assumption, where you need to sell into a flat market and währing costs eat the margin.
Compare that to the risk-adjusted return on the best available Australian opportunity, factoring in the new tax settings, and to non-property alternatives (ETFs, managed funds, offset account). Offshore property might win that comparison. But it should have to clear a higher bar than the domestic equivalent, because the unknowns are larger.
If you’re a local buyer or renter watching this unfold, the practical impact depends on how much of that search activity converts. A genuine capital shift offshore would ease price pressure in the investor-heavy segments of Sydney, Brisbane and Perth, and potentially slow some supply projects. A search spike that doesn’t convert changes nothing. The data over the next two quarters, actual settlement volumes of Australian buyers in New Zealand, and presale rates on Australian off-the-plan stock, will show which scenario is playing out.
For more on how offshore investment fits into a diversified property strategy, read about using home equity to invest and the risks hidden in the numbers. If you want the weekly signal on where capital is moving and what it means for your next decision, subscribe to the Australian Property Review newsletter.
General info, not financial advice.