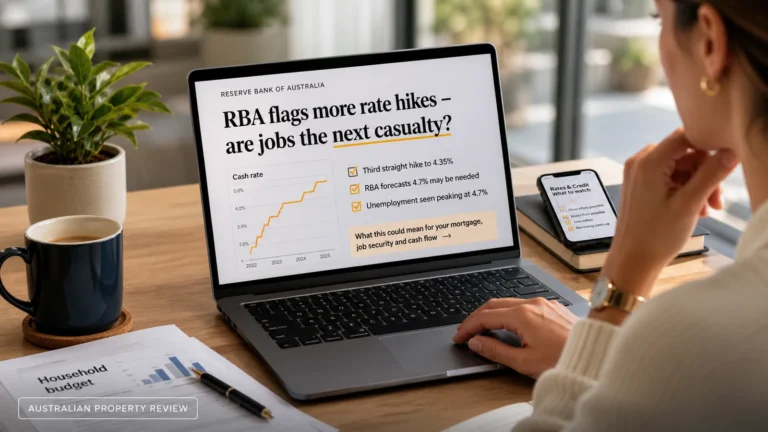
The latest lending figures show a market being pulled back from two directions at once. In the twelve months to September, loans to property investors fell 38%. Loans to owner-occupiers slipped 4.6%. If you are asking who benefits from interest rate rises, the early answer looks like nobody in the housing chain, at least in the short run.
The investor number needs context. Two things are driving it. A scaled-back capital gains tax discount has reduced the appeal of holding property for growth. And the comparison point is unusually high: investor lending jumped 18% in the September quarter of 2024, when buyers rushed in ahead of a government scheme letting first home buyers purchase with a 5% deposit. Part of the 38% fall is policy working as intended. Part is a hangover from a rush.
Why the investor drop is mostly a tax story
The tax change looks to be doing what it was designed to do on investors. Owner-occupier lending tells a different story. Its softer fall of 4.6% has more to do with interest rates than with any tax setting. Our guide to negative gearing, CGT and investor tax explains how these settings shape investor returns, and why a smaller discount matters most for buyers relying on long-run price growth.
We have tracked the same pattern in earlier quarters. See our coverage of investor lending dropping 31pc and what that means for rental supply. Fewer investors usually means fewer new rentals, which is a pressure point for tenants rather than a relief.
What lending says about prices
Lending tends to lead prices by about six months. On that reading, values are flat to falling, with early signs of declines in some places. Official price data is due in roughly two weeks, which will show how far the pullback has already reached the numbers buyers see.
That is a base case, not a certainty. Prices can hold up for a while if sellers pull listings rather than cut. But when both investor and owner-occupier credit are shrinking, the bias is toward softness.
The household squeeze behind owner-occupier weakness
The owner-occupier slide is mainly a household budget story. Rate rises have landed on borrowers while wages grow slowly and unemployment climbs. In Western Australia, average loan sizes have risen 53% in three years, against wage growth of 11.6%. A $730,000 loan now costs $5,772 more a year in repayments.
Nationally, average loan growth has eased to 5.8%. That suggests lenders and borrowers are both recalibrating, and that serviceability, not demand, is the binding constraint. Our report on mortgage arrears hitting a six-year high as lending falls 15% shows where that strain can show up next.
Key numbers
- Investor loans: down 38% in the 12 months to September
- Owner-occupier loans: down 4.6% over the same period
- Investor lending in the September 2024 quarter: up 18%
- Extra annual cost on a $730,000 loan: $5,772
- Average loan growth nationally: 5.8%
The trade-off the rate-peak story underplays
Here is the catch. A peak in rates is being read as good news for buyers. It may be. But the same weak demand now chilling the market also reaches the people who build homes.
Construction loans are falling. Input costs are rising, partly because datacentre demand tied to AI is competing for materials and trades. Copper pipes are up 33% and electrical cabling is up 26% in nine months. Builders facing dearer inputs and thinner lending have less reason to start new projects.
That is a second-order effect worth watching. Policy and rate settings that cut investor demand reduce the pipeline of buyers. At the same time, softer construction activity and rising joblessness thin out the trades needed to deliver supply later. Cooling demand now can mean tighter supply when conditions turn. That is not a reason to avoid the tax changes or the rate peak. It is a reason not to treat a rate peak as a clean win.
Rate cuts may come after the pain, not before it
Markets expect a cut, possibly two within 18 months. The timing is the point. Cuts would likely follow higher unemployment, not precede it. For a worker, that means the relief may arrive after the job-market damage rather than in time to prevent it.
For borrowers, the practical read is a buffer first, optimism second. If you are on a variable rate, test your repayments against today’s cost, not a hoped-for cut. If you are an investor, price in a smaller tax benefit and a softer growth outlook before you commit. If you are a buyer, a flat market gives you time, but only if your income is secure. Our look at the record quarterly drop in investor home loans is a useful companion on what thinner investor activity means for rents.
The next step is simple: wait for the official price data in about two weeks, then set it against the lending trend before making a decision.
If you want the weekly signal, subscribe to the free newsletter.
General info, not financial advice.